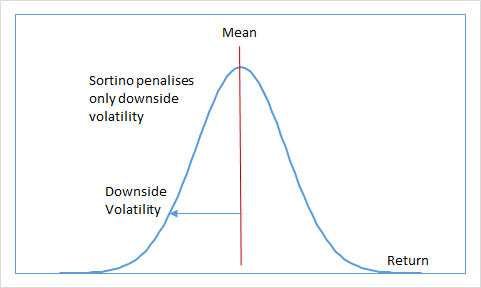
Sharpe-Ratio und Sortino-Ratio
Finanzhandel mit Python

Chelsea Yang
Data Science Instructor
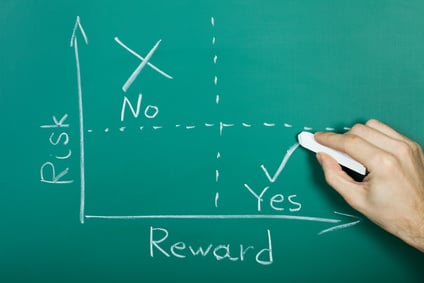
Risikobereinigte Rendite
- Leistung zwischen Strategien vergleichbar machen
- Ein Verhältnis, das das Risiko zur Rendite beschreibt
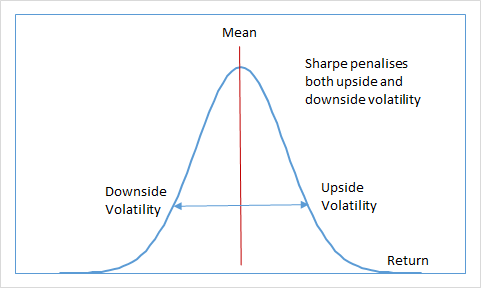
Einschränkungen der Sharpe-Ratio
- Bestraft sowohl „gute" als auch „schlechte" Volatilität
- Aufwärtsvolatilität kann das Verhältnis nach unten verzerren
Sortino-Ratio
$$ \text{Sortino Ratio} = (R_p - R_r)/\sigma_d $$
- $R_p $: Rendite einer Strategie, eines Portfolios, Assets usw.
- $R_r $: Risikofreier Zins
- $\sigma_d $: Downside-Deviation der Überschussrendite ($R_p-R_f$)