Các yếu tố ảnh hưởng đến độ lồi

Định giá và Phân tích Trái phiếu bằng Python

Joshua Mayhew

Options Trader

Độ lồi là lợi ích

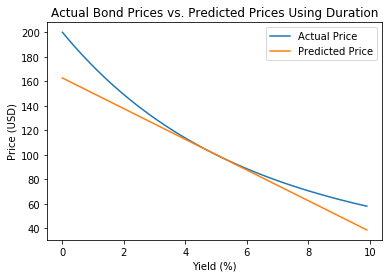
  • Giá trái phiếu tăng mạnh hơn khi lợi suất giảm, giảm nhẹ hơn khi lợi suất tăng

Định giá và Phân tích Trái phiếu bằng Python

Khám phá độ lồi

  • So sánh trực tiếp độ lồi của hai trái phiếu
  • Vẽ đồ thị yếu tố so với độ lồi
  • Quan sát trực tiếp độ cong của quan hệ giá/lợi suất
Định giá và Phân tích Trái phiếu bằng Python

Coupon vs. độ lồi

  • Trái phiếu 10 năm lợi suất 5%: trái phiếu 1 không có coupon, trái phiếu 2 coupon 10%
price_1 = -npf.pv(rate=0.05, nper=10, pmt=0, fv=100)

price_up_1 = -npf.pv(rate=0.06, nper=10, pmt=0, fv=100)
price_down_1 = -npf.pv(rate=0.04, nper=10, pmt=0, fv=100)
convexity_1 = (price_down_1 + price_up_1 - 2 * price_1) / (price_1 * 0.01 ** 2)
price_2 = -npf.pv(rate=0.05, nper=10, pmt=10, fv=100)
price_up_2 = -npf.pv(rate=0.06, nper=10, pmt=10, fv=100)
price_down_2 = -npf.pv(rate=0.04, nper=10, pmt=10, fv=100)
convexity_2 = (price_down_2 + price_up_2 - 2 * price_2) / (price_2 * 0.01 ** 2)
print("Low Coupon Bond Convexity: ", convexity_1)
print("High Coupon Bond Convexity: ", convexity_2)
Low Coupon Bond Convexity:  99.89
High Coupon Bond Convexity:  64.09
Định giá và Phân tích Trái phiếu bằng Python

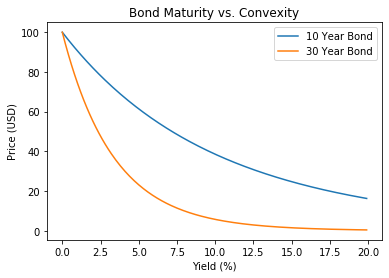
Kỳ hạn vs. độ lồi

bond_yields = np.arange(0, 20, 0.1)
bond = pd.DataFrame(bond_yields, columns=['yield'])
bond['price_10y'] = -npf.pv(rate=bond['yield'] / 100, 
    nper=10, pmt=0, fv=100)
bond['price_30y'] = -npf.pv(rate=bond['yield'] / 100, 
    nper=30, pmt=0, fv=100)
plt.plot(bond['yield'], bond['price_10y'])
plt.plot(bond['yield'], bond['price_30y'])
plt.xlabel('Yield (%)')
plt.ylabel('Price (USD)')
plt.title('Bond Maturity vs. Convexity')
plt.legend(["10 Year Bond", "30 Year Bond"])
plt.show()

Định giá và Phân tích Trái phiếu bằng Python

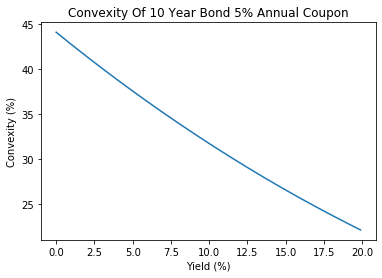
Lợi suất vs. độ lồi

bond_yields = np.arange(0, 20, 0.1)
bond = pd.DataFrame(bond_yields, columns=['bond_yield'])

bond['price'] = -npf.pv(rate=bond['bond_yield'] / 100, nper=10, pmt=5, fv=100)
bond['price_up'] = -npf.pv(rate=bond['bond_yield'] / 100 
    + 0.01, nper=10, pmt=5, fv=100)
bond['price_down'] = -npf.pv(rate=bond['bond_yield'] / 100 
    - 0.01, nper=10, pmt=5, fv=100)
bond['convexity'] = (bond['price_down'] + bond['price_up'] 
- 2 * bond['price']) / (bond['price'] * 0.01 ** 2)
plt.plot(bond['bond_yield'], bond['convexity'])
plt.xlabel('Yield (%)')
plt.ylabel('Convexity (%)')
plt.title("Convexity Of 10 Year Bond 5% Annual Coupon")
plt.show()

Định giá và Phân tích Trái phiếu bằng Python

Tóm tắt

  • Độ lồi dương là lợi ích:
    • Giảm lỗ khi lợi suất tăng, tăng lãi khi lợi suất giảm


  • Độ lồi tăng khi trái phiếu có:
    • Kỳ hạn cao hơn
    • Coupon thấp hơn
    • Lợi suất thấp hơn
Định giá và Phân tích Trái phiếu bằng Python

Vamos praticar!

Định giá và Phân tích Trái phiếu bằng Python

Preparing Video For Download...