R による生命保険商品の評価
Katrien Antonio, Ph.D.
Professor, KU Leuven and University of Amsterdam
保険料計算の目的:
解決策:
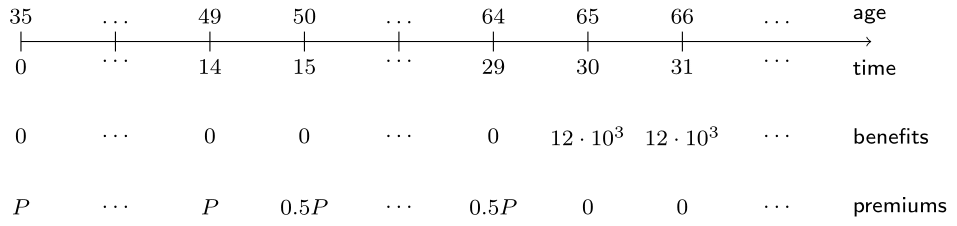
インクレディブル夫人は35歳です。
65歳から生涯にわたり年間12,000ユーロを受け取る生命年金の購入を希望しています。
35歳から30年間、年払い保険料でこの商品を積み立てます。保険料は15年後に半額になります。
初回保険料はいくらですか?
35歳、ベルギー在住、2013年。
利率は3%。
生存確率
# Survival probabilities of (35)
kpx <- c(1, cumprod(px[(35 + 1):length(px)]))
割引係数
# Discount factors
discount_factors <- (1 + 0.03) ^ - (0:(length(kpx) - 1))
給付金
# Benefits
benefits <- c(rep(0, 30), rep(12000, length(kpx) - 30))
# EPV of the life annuity benefits
sum(benefits * discount_factors * kpx)
70928.84
保険料パターン rho
# Premium pattern rho
rho <- c(rep(1, 15), rep(0.5, 15), rep(0, length(kpx) - 30))
# EPV of the premium pattern
sum(rho * discount_factors * kpx)
16.01978
$$ P = \frac{\text{EPV}(\text{benefits})}{\text{EPV}(\text{rho})}. $$
# The ratio of the EPV of the life annuity benefits
# and the EPV of the premium pattern
sum(benefits * discount_factors * kpx) / sum(rho * discount_factors * kpx)
4427.578