期間変更と金利の期間構造
R による生命保険商品の評価

Roel Verbelen, Ph.D.
Statistician, Finity Consulting
年利率から $m$ 分割利率へ
年利率 $i$。
$1/m$ 年の期間に適用される利率 $i^{\star}_m$ を求めるには?
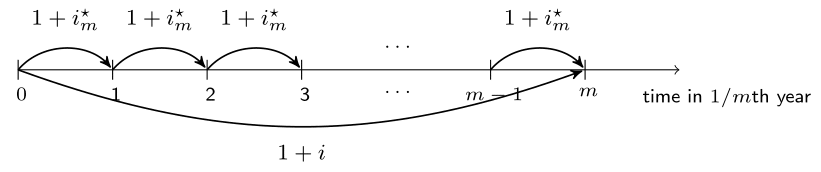
$\qquad$ すると:
$$ 1+i = (1+i^{\star}_m)^m \quad \Leftrightarrow \quad i^{\star}_m = (1+i)^{1/m}-1. $$
Rにおける年利率から $m$ 分割利率への変換
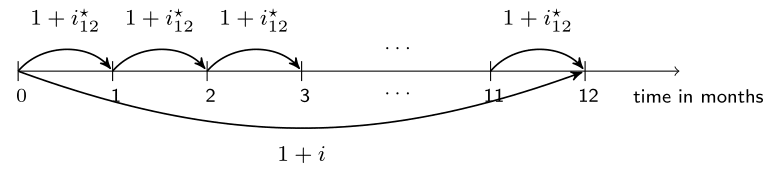
非一定金利
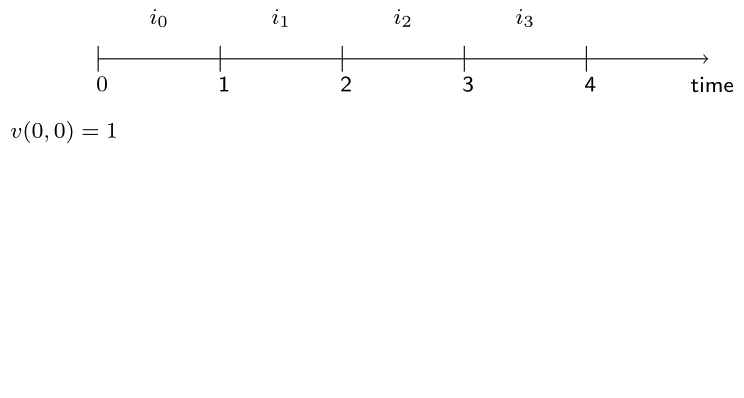
非一定金利
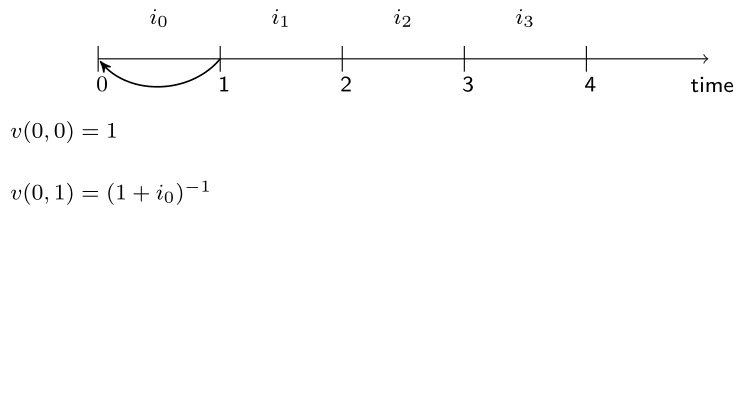
非一定金利
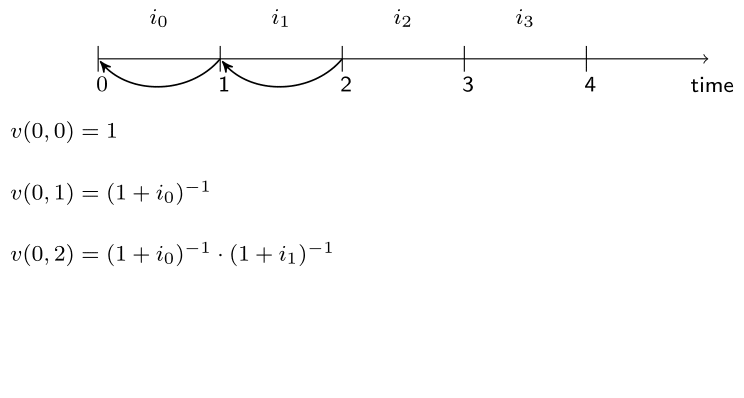
非一定金利
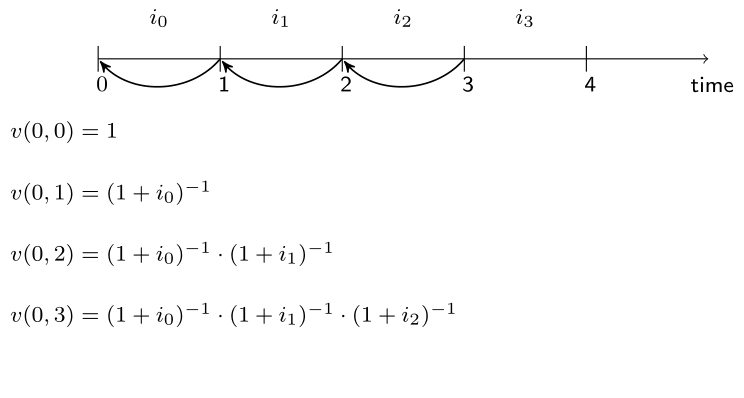
非一定金利
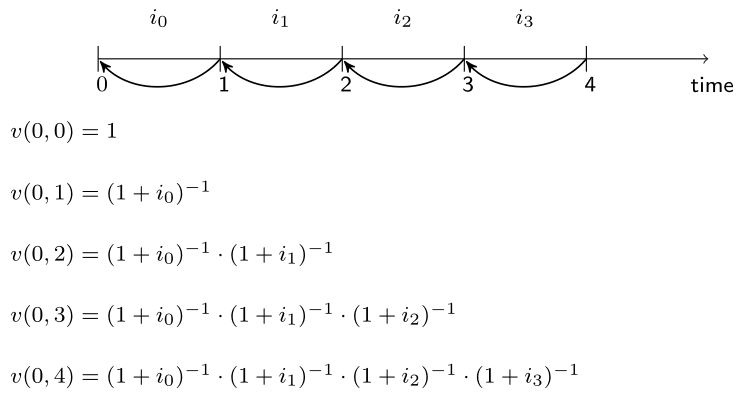
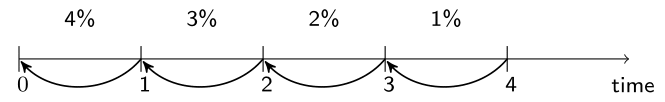
# Define the vector containing the interest rates
interest <- c(0.04, 0.03, 0.02, 0.01)
# Define the vector containing the inverse of 1 plus the interest rate
yearly_discount_factors <- (1 + interest) ^ - 1
# Define the discount factors to time 0 using cumprod()
discount_factors <- c(1 , cumprod(yearly_discount_factors))
discount_factors
1.0000000 0.9615385 0.9335325 0.9152279 0.9061663

