White noise (WN) मॉडल

R में Time Series Analysis

David S. Matteson

Associate Professor at Cornell University

White noise

White Noise (WN) एक stationary प्रक्रिया का सबसे सरल उदाहरण है.

एक weak white noise प्रक्रिया में होता है:

  • एक तय, स्थिर mean.
  • एक तय, स्थिर variance.
  • समय के साथ कोई correlation नहीं.
R में Time Series Analysis

White noise

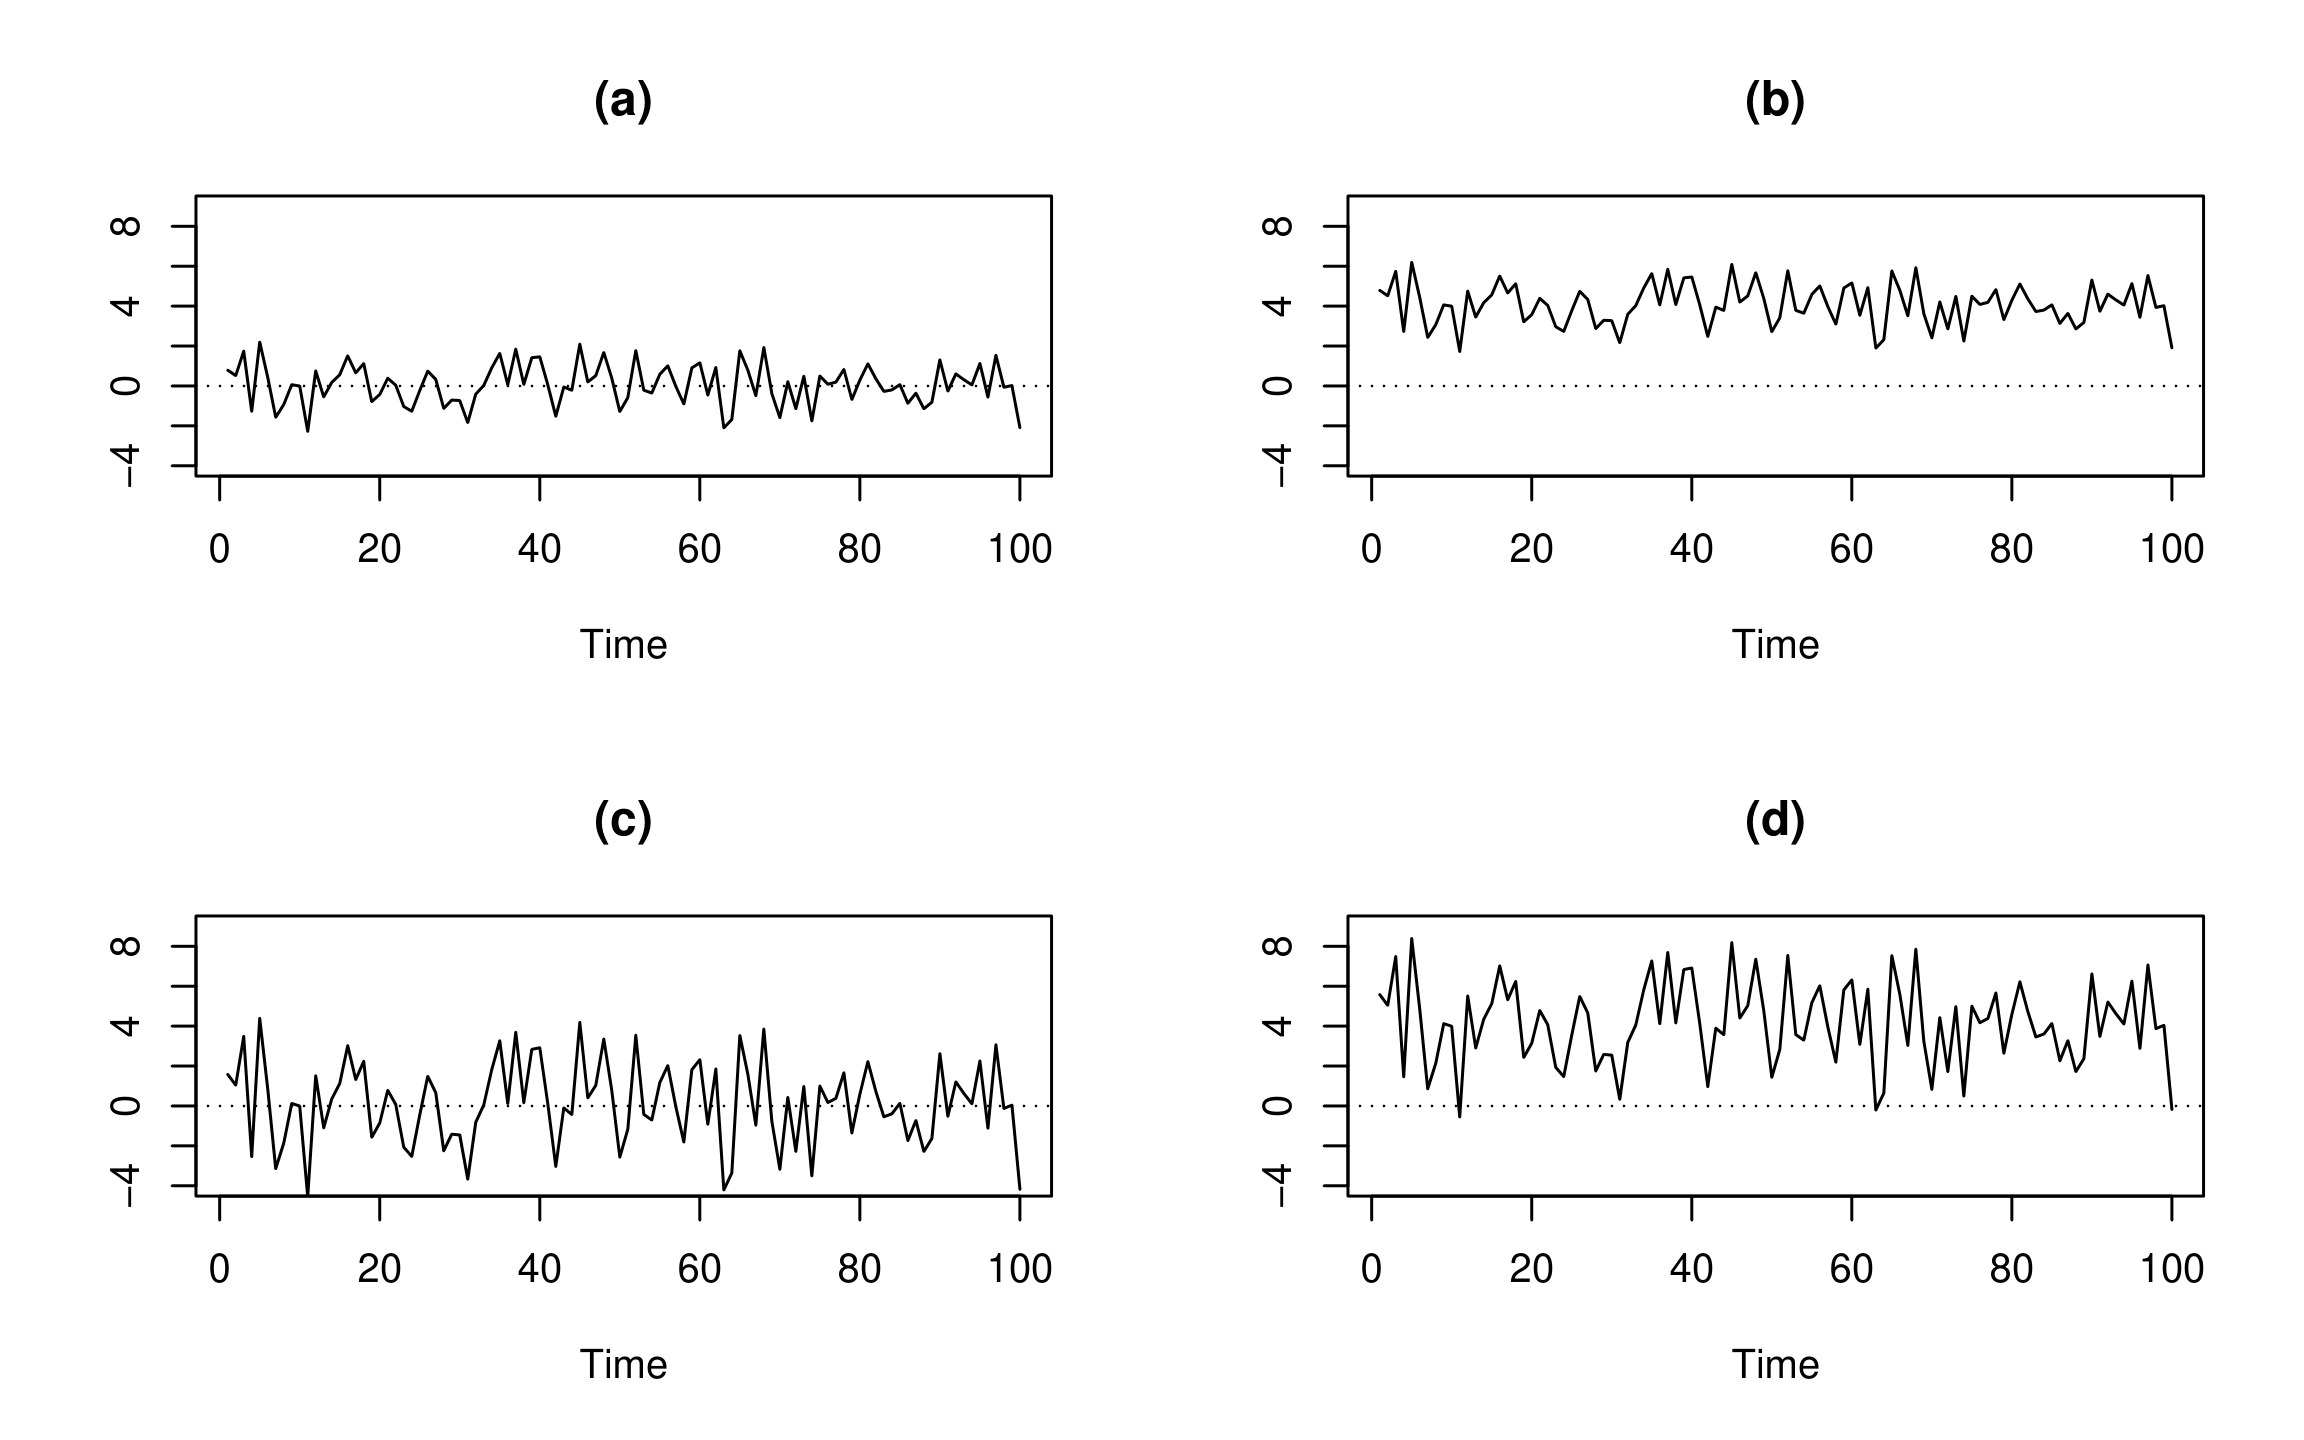
White Noise के time series plots:
R में Time Series Analysis

White noise

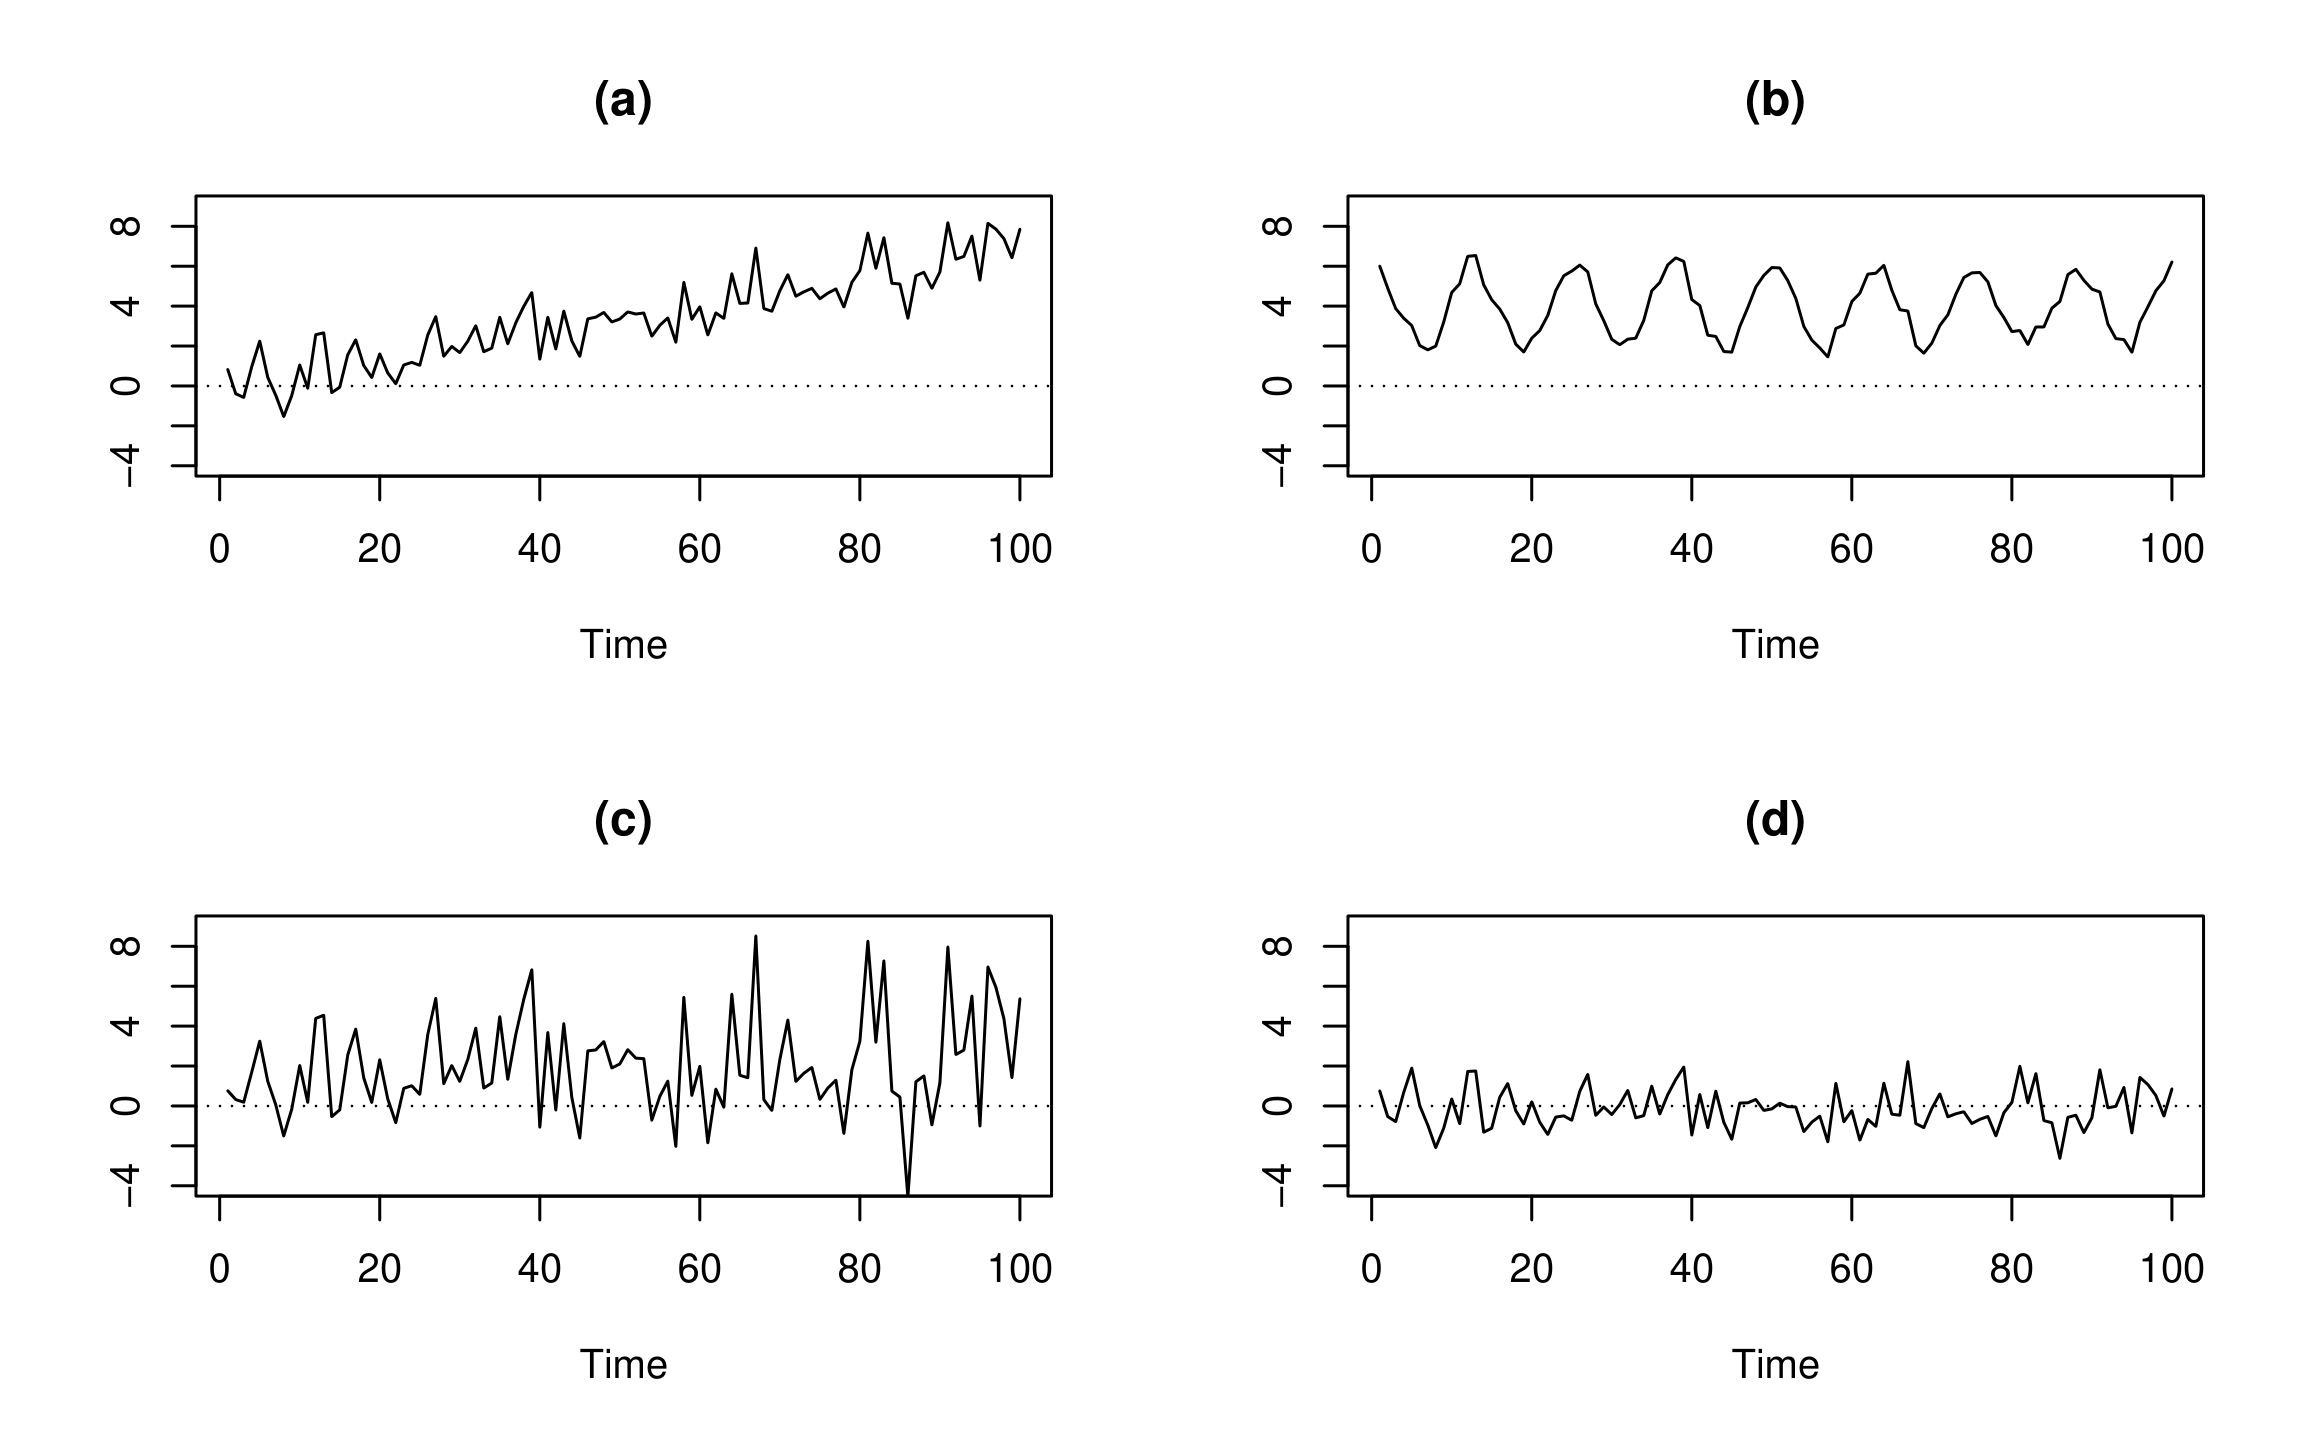
White Noise के time series plots?
R में Time Series Analysis
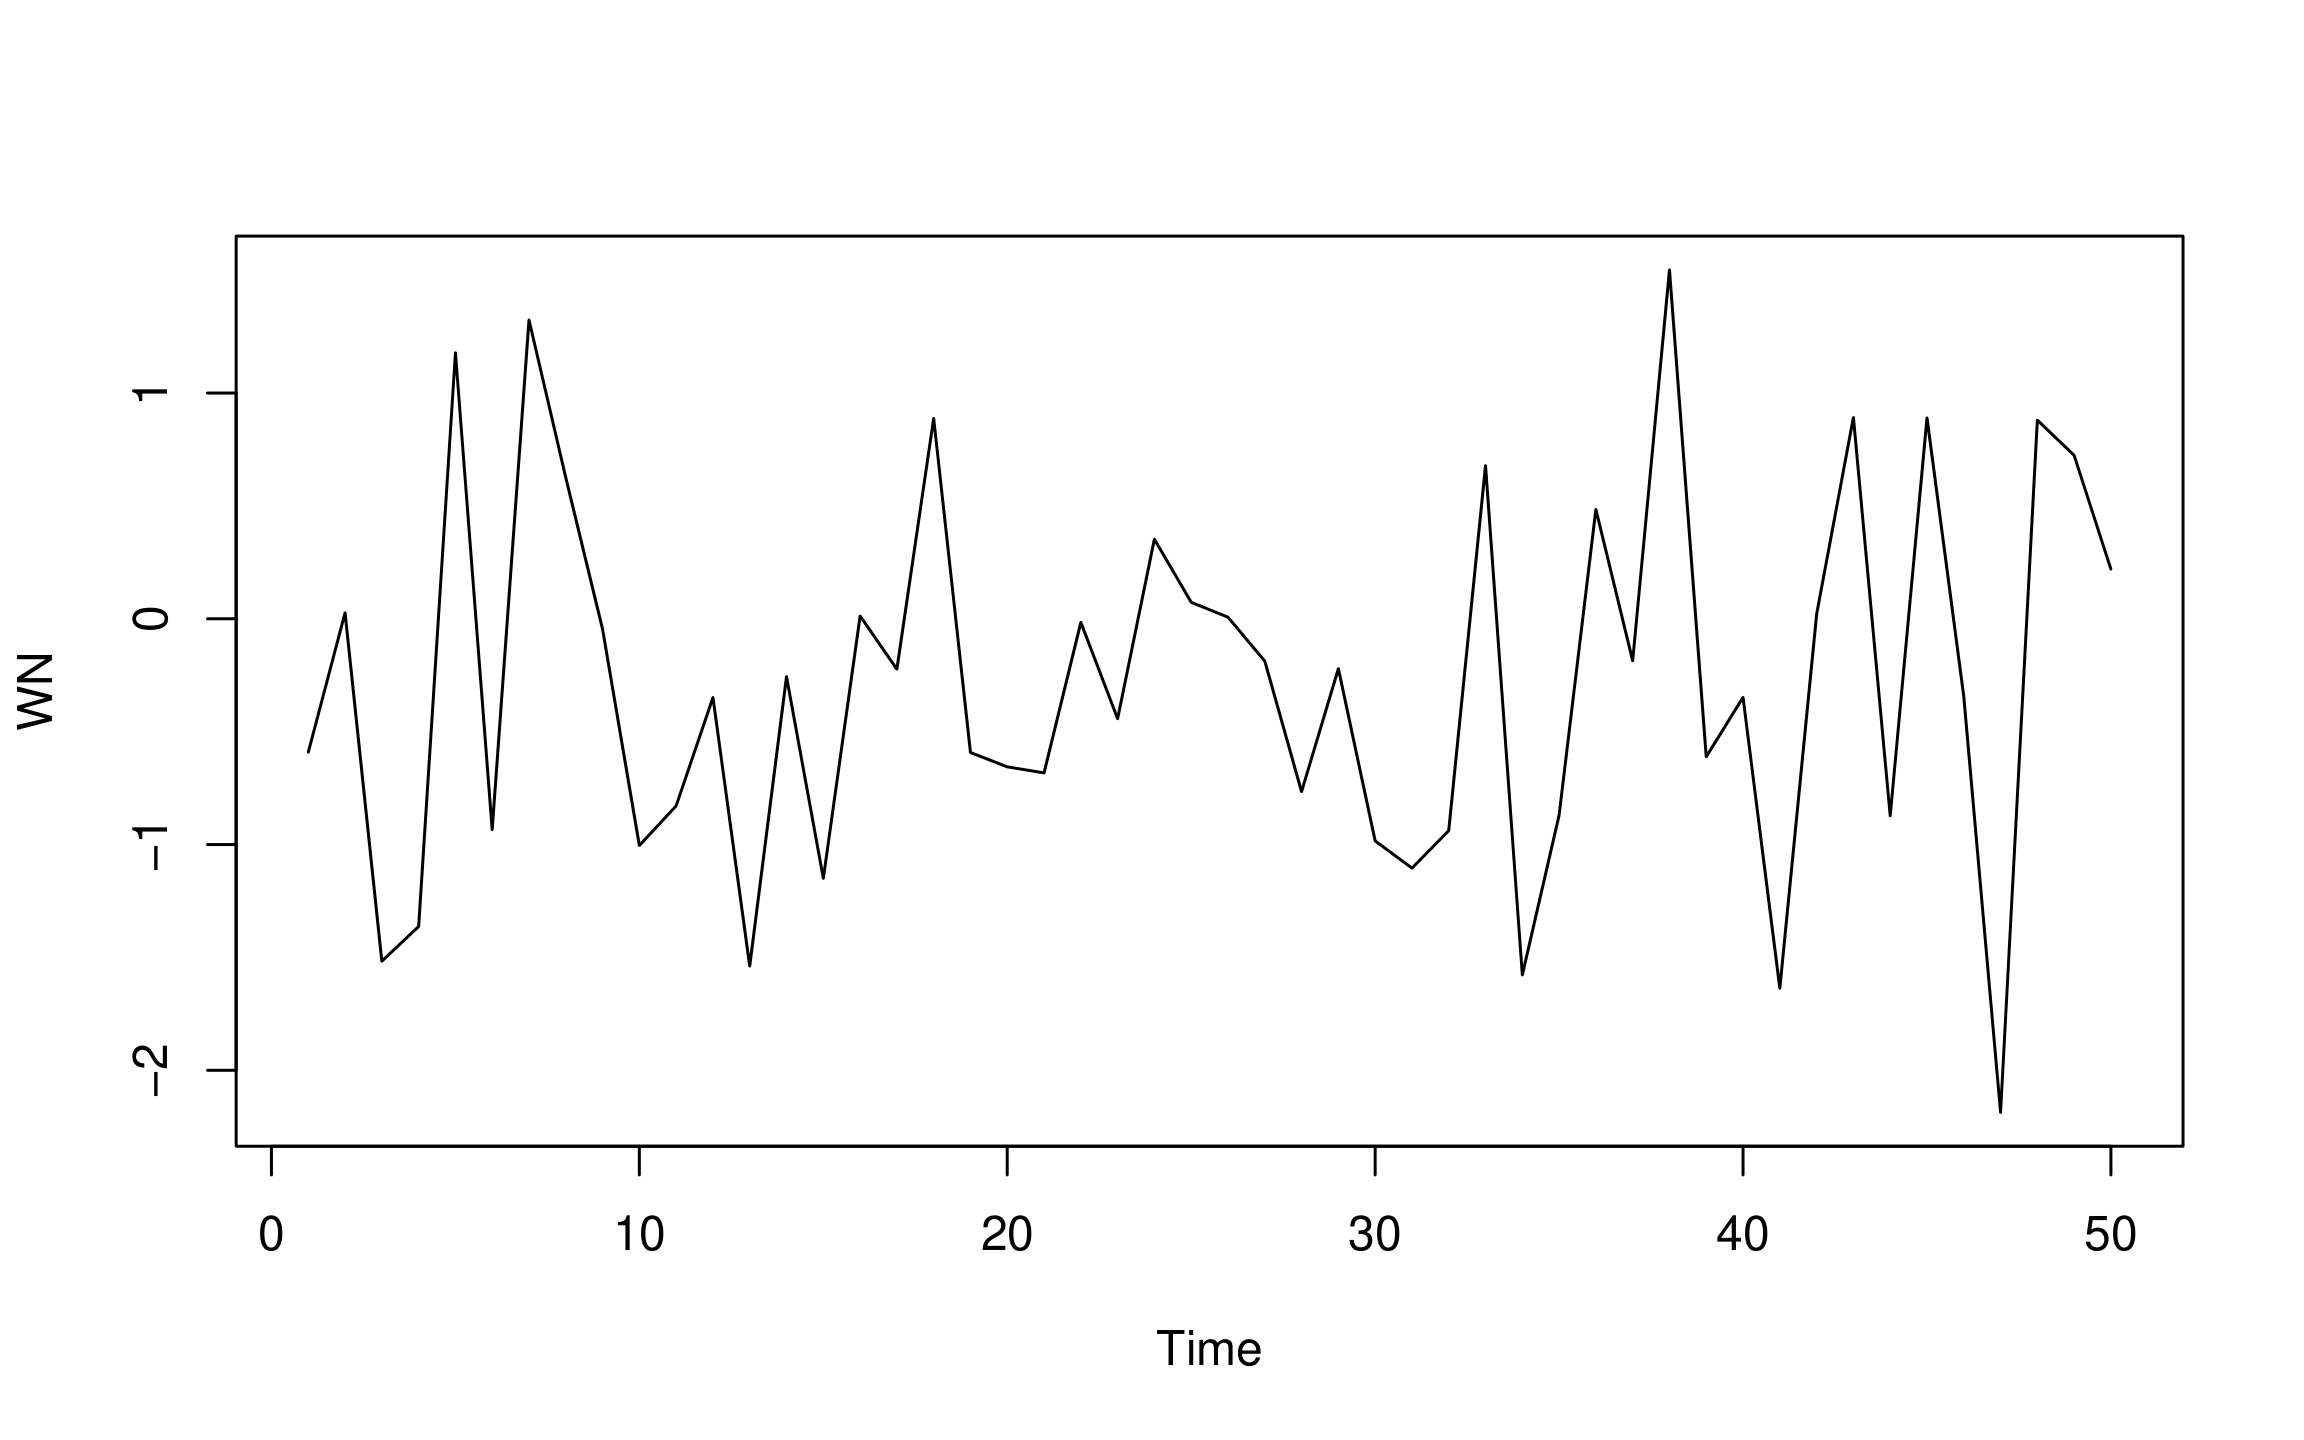
# Simulate n = 50 observations from the WN model
WN_1 <- arima.sim(model = list(order = c(0, 0, 0)), n = 50)
head(WN_1)
-0.005052984  0.042669765  3.261154066  
 2.486431235  0.283119322  1.543525773
ts.plot(WN_1)
R में Time Series Analysis
# Simulate from the WN model with mean = 4, sd = 2
WN_2 <- arima.sim(model = list(order = c(0, 0, 0)), 
                  n = 50, mean = 4, sd = 2)
ts.plot(WN_2)

R में Time Series Analysis

White noise का estimation

# Fit the WN model with 
# arima()
arima(WN_2, 
      order = c(0, 0, 0))
Coefficients:
      intercept
         4.0739
s.e.     0.2698
sigma^2 estimated as 3.639
# Calculate the sample 
# mean and sample variance
# of WN
mean(WN_2)
4.0739
var(WN_2)
3.713
R में Time Series Analysis

अभ्यास करते हैं!

R में Time Series Analysis

Preparing Video For Download...