शीन्केज़ विधियाँ

R में Feature Engineering

Jorge Zazueta

Research Professor and Head of the Modeling Group at the School of Economics, UASLP

दो आम रेग्युलराइज़ेशन तकनीकें

Lasso

  • मॉडल वेट्स के परिमाण के अनुपात में पेनल्टी जोड़ता है
  • कुछ वेट्स को ठीक-ठीक शून्य होने के लिए प्रेरित करता है
  • संबंधित फीचर्स को प्रभावी रूप से हटाता है
  • ऑटोमेटेड फीचर चयन का तरीका हो सकता है

Ridge

  • मॉडल वेट्स के वर्ग के अनुपात में पेनल्टी जोड़ता है
  • Lasso की तरह कुछ गुणांकों को शून्य तक नहीं घटाता
  • लेकिन ओवरफिटिंग को प्रभावी रूप से कम कर सकता है
R में Feature Engineering

Lasso की पहली झलक

मॉडल सेट करें

recipe <- # Define recipe
recipe(Loan_Status ~ ., data = train) %>%
  step_normalize(all_numeric_predictors()) %>% 
  step_dummy(all_nominal_predictors()) %>%
  update_role(Loan_ID, new_role = "ID")
# set up model
model_lasso_manual <- logistic_reg() %>%
  set_engine("glmnet") %>%
  set_args(mixture = 1, penalty = .2)
# Bundle in workflow
workflow_lasso_manual <-
  workflow() %>%
  add_model(model_lasso_manual) %>%
  add_recipe(recipe)

फिट करें और जाँचें

fit_lasso_manual <- # Fit workflow
  workflow_lasso_manual %>% 
  fit(train)
#Inspect coefficients
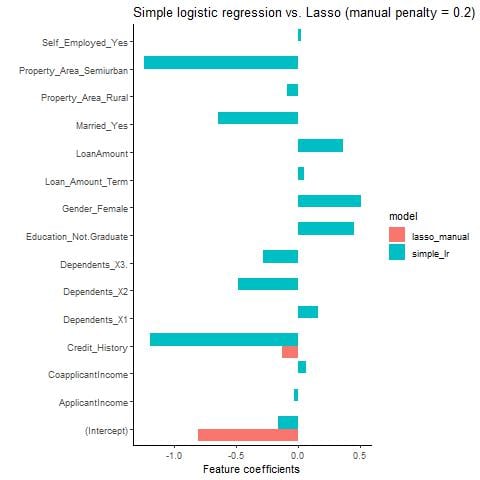
tidy(fit_lasso_manual)
# A tibble: 15 × 3
   term                    estimate penalty
   <chr>                      <dbl>   <dbl>
 1 (Intercept)               -0.816     0.2
 2 ApplicantIncome            0         0.2
 3 CoapplicantIncome          0         0.2
 4 LoanAmount                 0         0.2
 5 Loan_Amount_Term           0         0.2
 6 Credit_History            -0.220     0.2
 7 Gender_Female              0         0.2
 ...                          ...        ...
R में Feature Engineering

सिंपल लॉजिस्टिक रिग्रेशन बनाम Lasso

सिंपल लॉजिस्टिक रिग्रेशन बनाम Lasso का कॉलम चार्ट.

R में Feature Engineering

हाइपरपैरामीटर ट्यूनिंग

ट्यूनिंग के साथ मॉडल सेट करना

model_lasso_tuned <- logistic_reg() %>%
  set_engine("glmnet") %>%
  set_args(mixture = 1, 
  penalty = tune()) 

workflow_lasso_tuned <-
  workflow() %>%
  add_model(model_lasso_tuned) %>%
  add_recipe(recipe)

penalty_grid <- grid_regular(
  penalty(range = c(-3, 1)),
  levels = 30)

ट्यूनिंग आउटपुट देखें

tune_output <- tune_grid( 
  workflow_lasso_tuned,
  resamples = vfold_cv(train, v = 5),
  metrics = metric_set(roc_auc),
  grid = penalty_grid)
autoplot(tune_output)
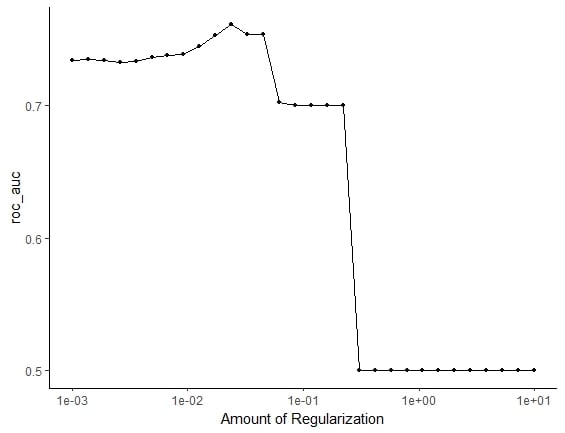
ROC_AUC बनाम रेग्युलराइज़ेशन की मात्रा का चार्ट.

R में Feature Engineering

परिणामों की जाँच

ऑटो-चुने गए फीचर्स

best_penalty <- 
select_by_one_std_err(tune_output, 
metric = 'roc_auc', desc(penalty)) 

# Fit Final Model
final_fit<- 
finalize_workflow(workflow_lasso_tuned, 
best_penalty) %>%
  fit(data = train)
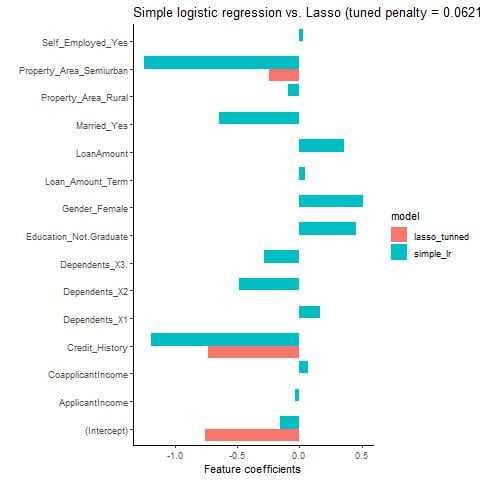
final_fit_se %>% tidy()
# A tibble: 15 × 3
   term                    estimate penalty
   <chr>                      <dbl>   <dbl>
 1 (Intercept)               -0.660  0.0452
 2 ApplicantIncome            0      0.0452
 3 CoapplicantIncome          0      0.0452
 4 LoanAmount                 0      0.0452
 5 Loan_Amount_Term           0      0.0452
 6 Credit_History            -0.948  0.0452
 7 Gender_Female              0      0.0452
 8 Married_Yes               -0.191  0.0452
 9 Dependents_X1              0      0.0452
10 Dependents_X2              0      0.0452
11 Dependents_X3.             0      0.0452
12 Education_Not.Graduate     0      0.0452
13 Self_Employed_Yes          0      0.0452
14 Property_Area_Rural        0      0.0452
15 Property_Area_Semiurban   -0.163  0.0452
R में Feature Engineering

सिंपल लॉजिस्टिक रिग्रेशन बनाम ट्यून किया हुआ Lasso
R में Feature Engineering

Ridge रेग्युलराइज़ेशन

mixture = 0 होने पर Ridge विकल्प है

model_ridge_tuned <- logistic_reg() %>%
  set_engine("glmnet") %>%
  set_args(mixture = 0, penalty = tune()) 

workflow_ridge_tuned <-
  workflow() %>%
  add_model(model_ridge_tuned) %>%
  add_recipe(recipe)

tune_output <- tune_grid( 
  workflow_ridge_tuned,
  resamples = vfold_cv(train, v = 5),
  metrics = metric_set(roc_auc),
  grid = penalty_grid)
tune_output <- tune_grid( 
  workflow_ridge_tuned,
  resamples = vfold_cv(train, v = 5),
  metrics = metric_set(roc_auc),
  grid = penalty_grid)  
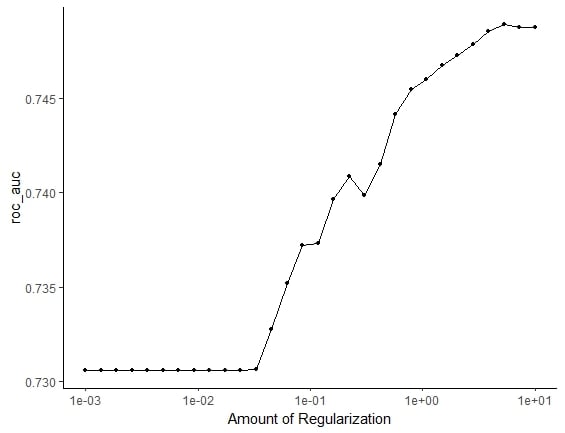
 autoplot(tune_output)
R में Feature Engineering

Ridge रेग्युलराइज़ेशन

best_penalty <- 
select_by_one_std_err(tune_output,
metric = 'roc_auc', desc(penalty)) 
best_penalty

final_fit<- 
finalize_workflow(workflow_ridge_tuned, 
best_penalty) %>%
  fit(data = train)
tidy(final_fit)
# A tibble: 15 × 3
   term                      estimate penalty
   <chr>                        <dbl>   <dbl>
 1 (Intercept)             -0.799          10
 2 ApplicantIncome          0.00232        10
 3 CoapplicantIncome        0.0000537      10
 4 LoanAmount               0.00291        10
 5 Loan_Amount_Term         0.00161        10
 6 Credit_History          -0.0245         10
 7 Gender_Female            0.00850        10
 8 Married_Yes             -0.0140         10
 9 Dependents_X1            0.00497        10
10 Dependents_X2           -0.0100         10
11 Dependents_X3.           0.00259        10
12 Education_Not.Graduate   0.00308        10
13 Self_Employed_Yes        0.00892        10
14 Property_Area_Rural      0.0109         10
15 Property_Area_Semiurban -0.0139         10
R में Feature Engineering

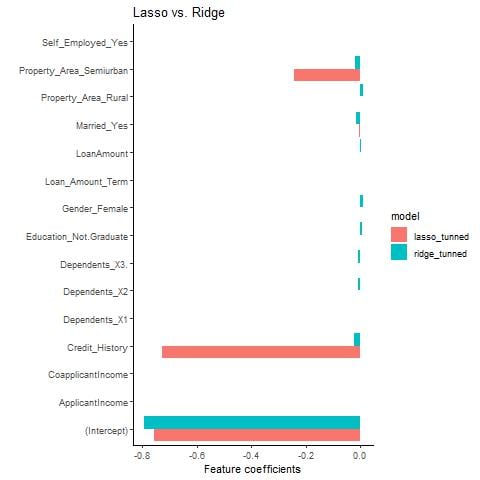
Ridge बनाम Lasso

R में Feature Engineering

अभ्यास करते हैं!

R में Feature Engineering

Preparing Video For Download...