resInfo = bt_result.stats

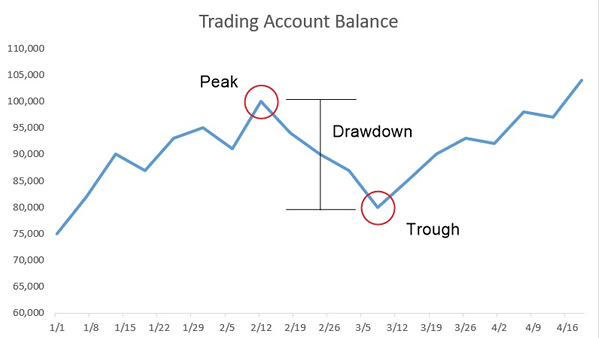
# Get the max drawdown
max_drawdown = resInfo.loc['max_drawdown']
print('Maximum drawdown: %.2f'% max_drawdown)

# Get the average drawdown
avg_drawdown = resInfo.loc['avg_drawdown']
print('Average drawdown: %.2f'% avg_drawdown)

# Get the average drawdown days
avg_drawdown_days = resInfo.loc['avg_drawdown_days']
print('Average drawdown days: %.0f'% avg_drawdown_days)
Maximum drawdown: -0.59
Average drawdown: -0.11
Average drawdown days: 22
resInfo = bt_result.stats
# Get the CAGR
cagr = resInfo.loc['cagr']
# Get the max drawdown
max_drawdown = resInfo.loc['max_drawdown']


# Calculate Calmar ratio mannually
calmar_calc = cagr / max_drawdown * (-1)
print('Calmar Ratio calculated: %.2f'% calmar_calc)
Calmar Ratio calculated: 4.14
從回測統計取得 Calmar 比率
resInfo = bt_result.stats

# Get the Calmar ratio
calmar = resInfo.loc['calmar']
print('Calmar Ratio: %.2f'% calmar)