動態諧波迴歸
R 的時間序列預測

Rob J. Hyndman
Professor of Statistics at Monash University
動態諧波迴歸
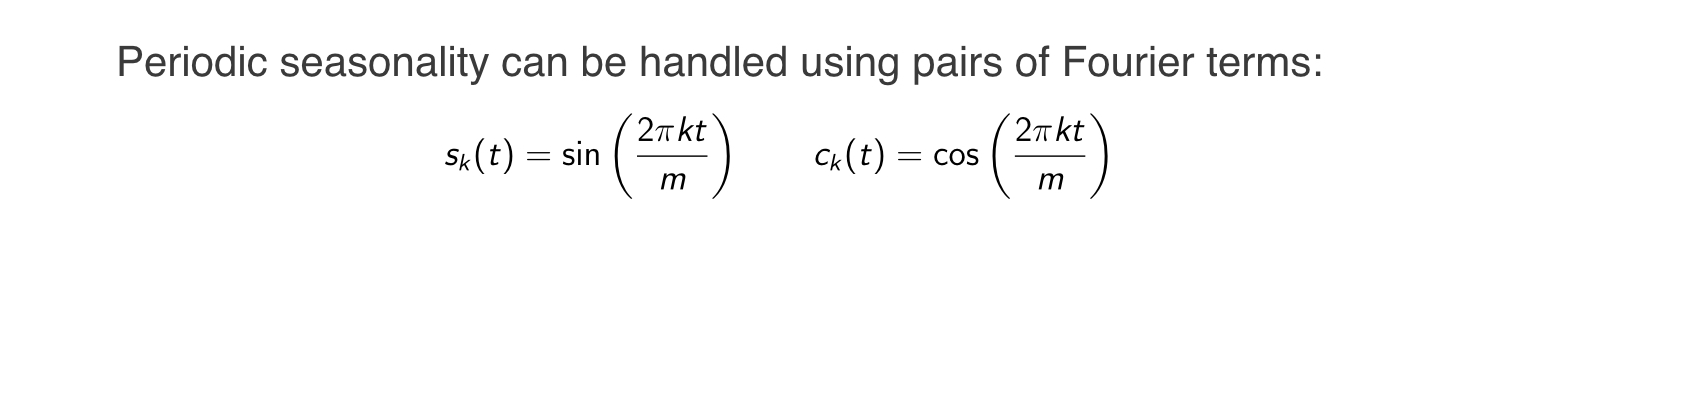
動態諧波迴歸
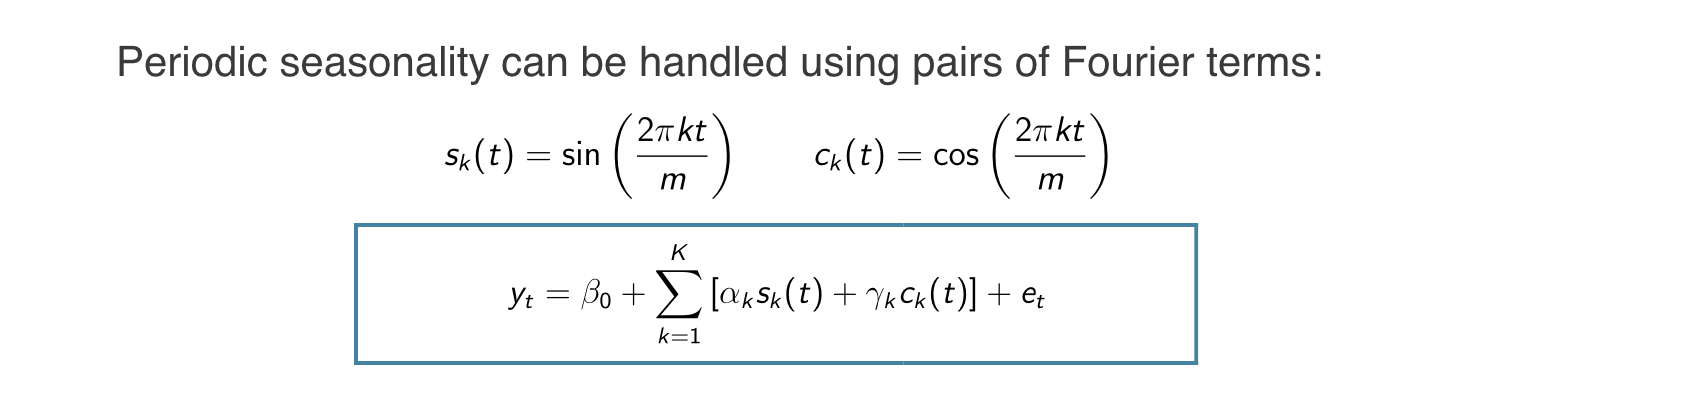
$m =$ 季節週期
任意週期函式在 K 足夠大時,可用 sin 與 cos 的和近似
迴歸係數:$\alpha_k$ 與 $\gamma_k$
$e_t$ 可建模為非季節性 ARIMA 流程
假設季節型態不變
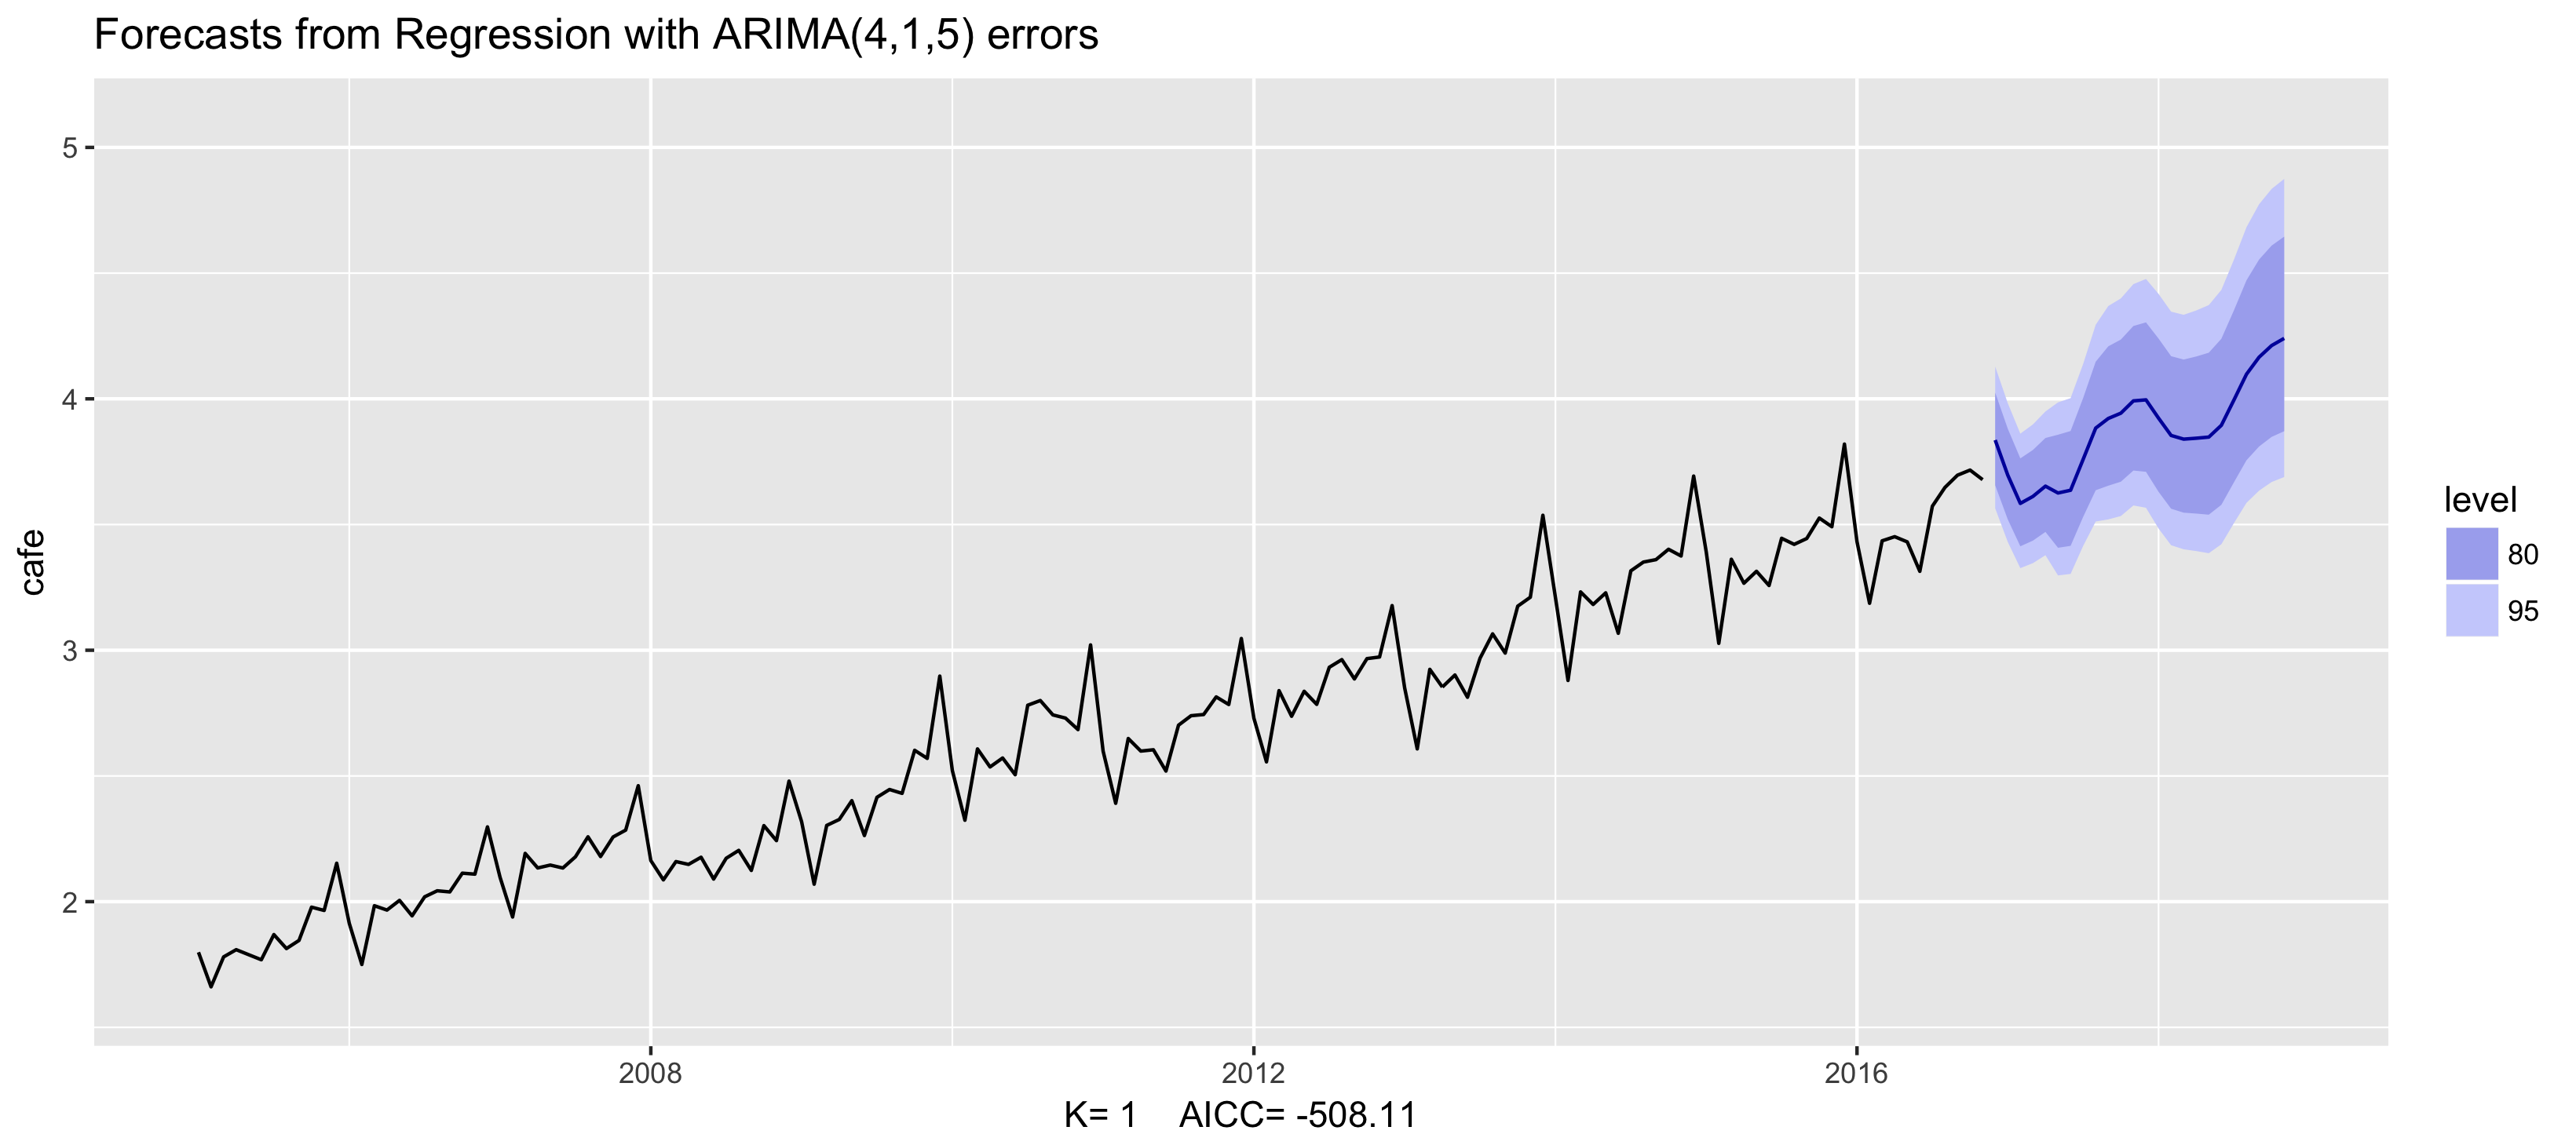
範例:澳洲咖啡館支出
fit <- auto.arima(cafe, xreg = fourier(cafe, K = 1),
                  seasonal = FALSE, lambda = 0)
fit %>% forecast(xreg = fourier(cafe, K = 1, h = 24)) %>%
   autoplot() + ylim(1.6, 5.1)
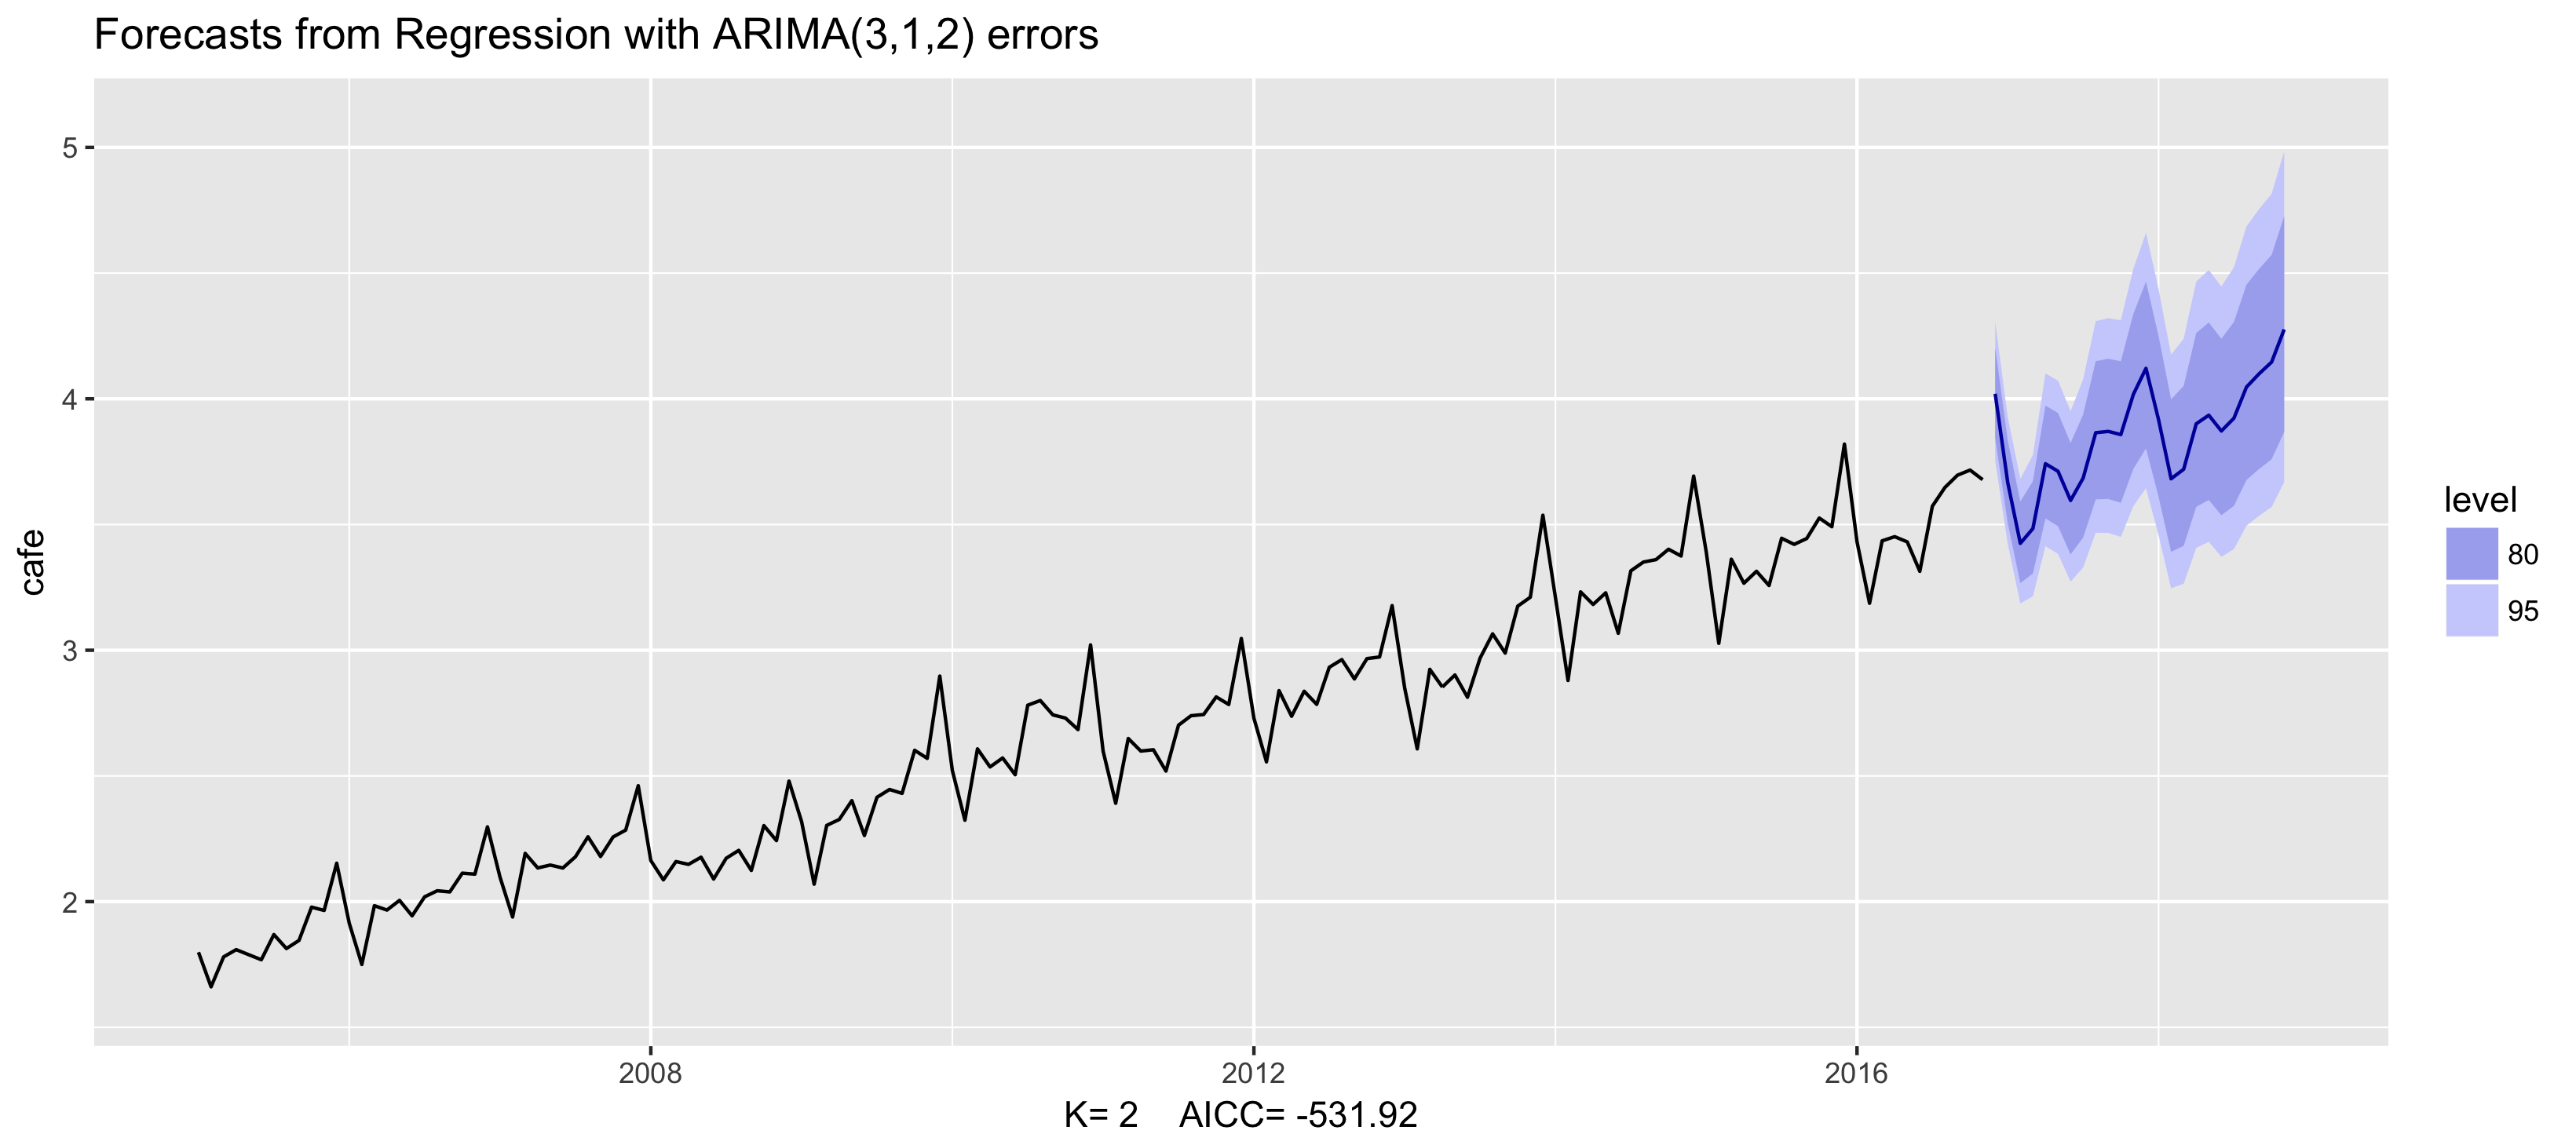
範例:澳洲咖啡館支出
fit <- auto.arima(cafe, xreg = fourier(cafe, K = 2),
                  seasonal = FALSE, lambda = 0)
fit %>% forecast(xreg = fourier(cafe, K = 2, h = 24)) %>%
   autoplot() + ylim(1.6, 5.1)
範例:澳洲咖啡館支出
fit <- auto.arima(cafe, xreg = fourier(cafe, K = 3),
                  seasonal = FALSE, lambda = 0)
fit %>% forecast(xreg = fourier(cafe, K = 3, h = 24)) %>%
   autoplot() + ylim(1.6, 5.1)
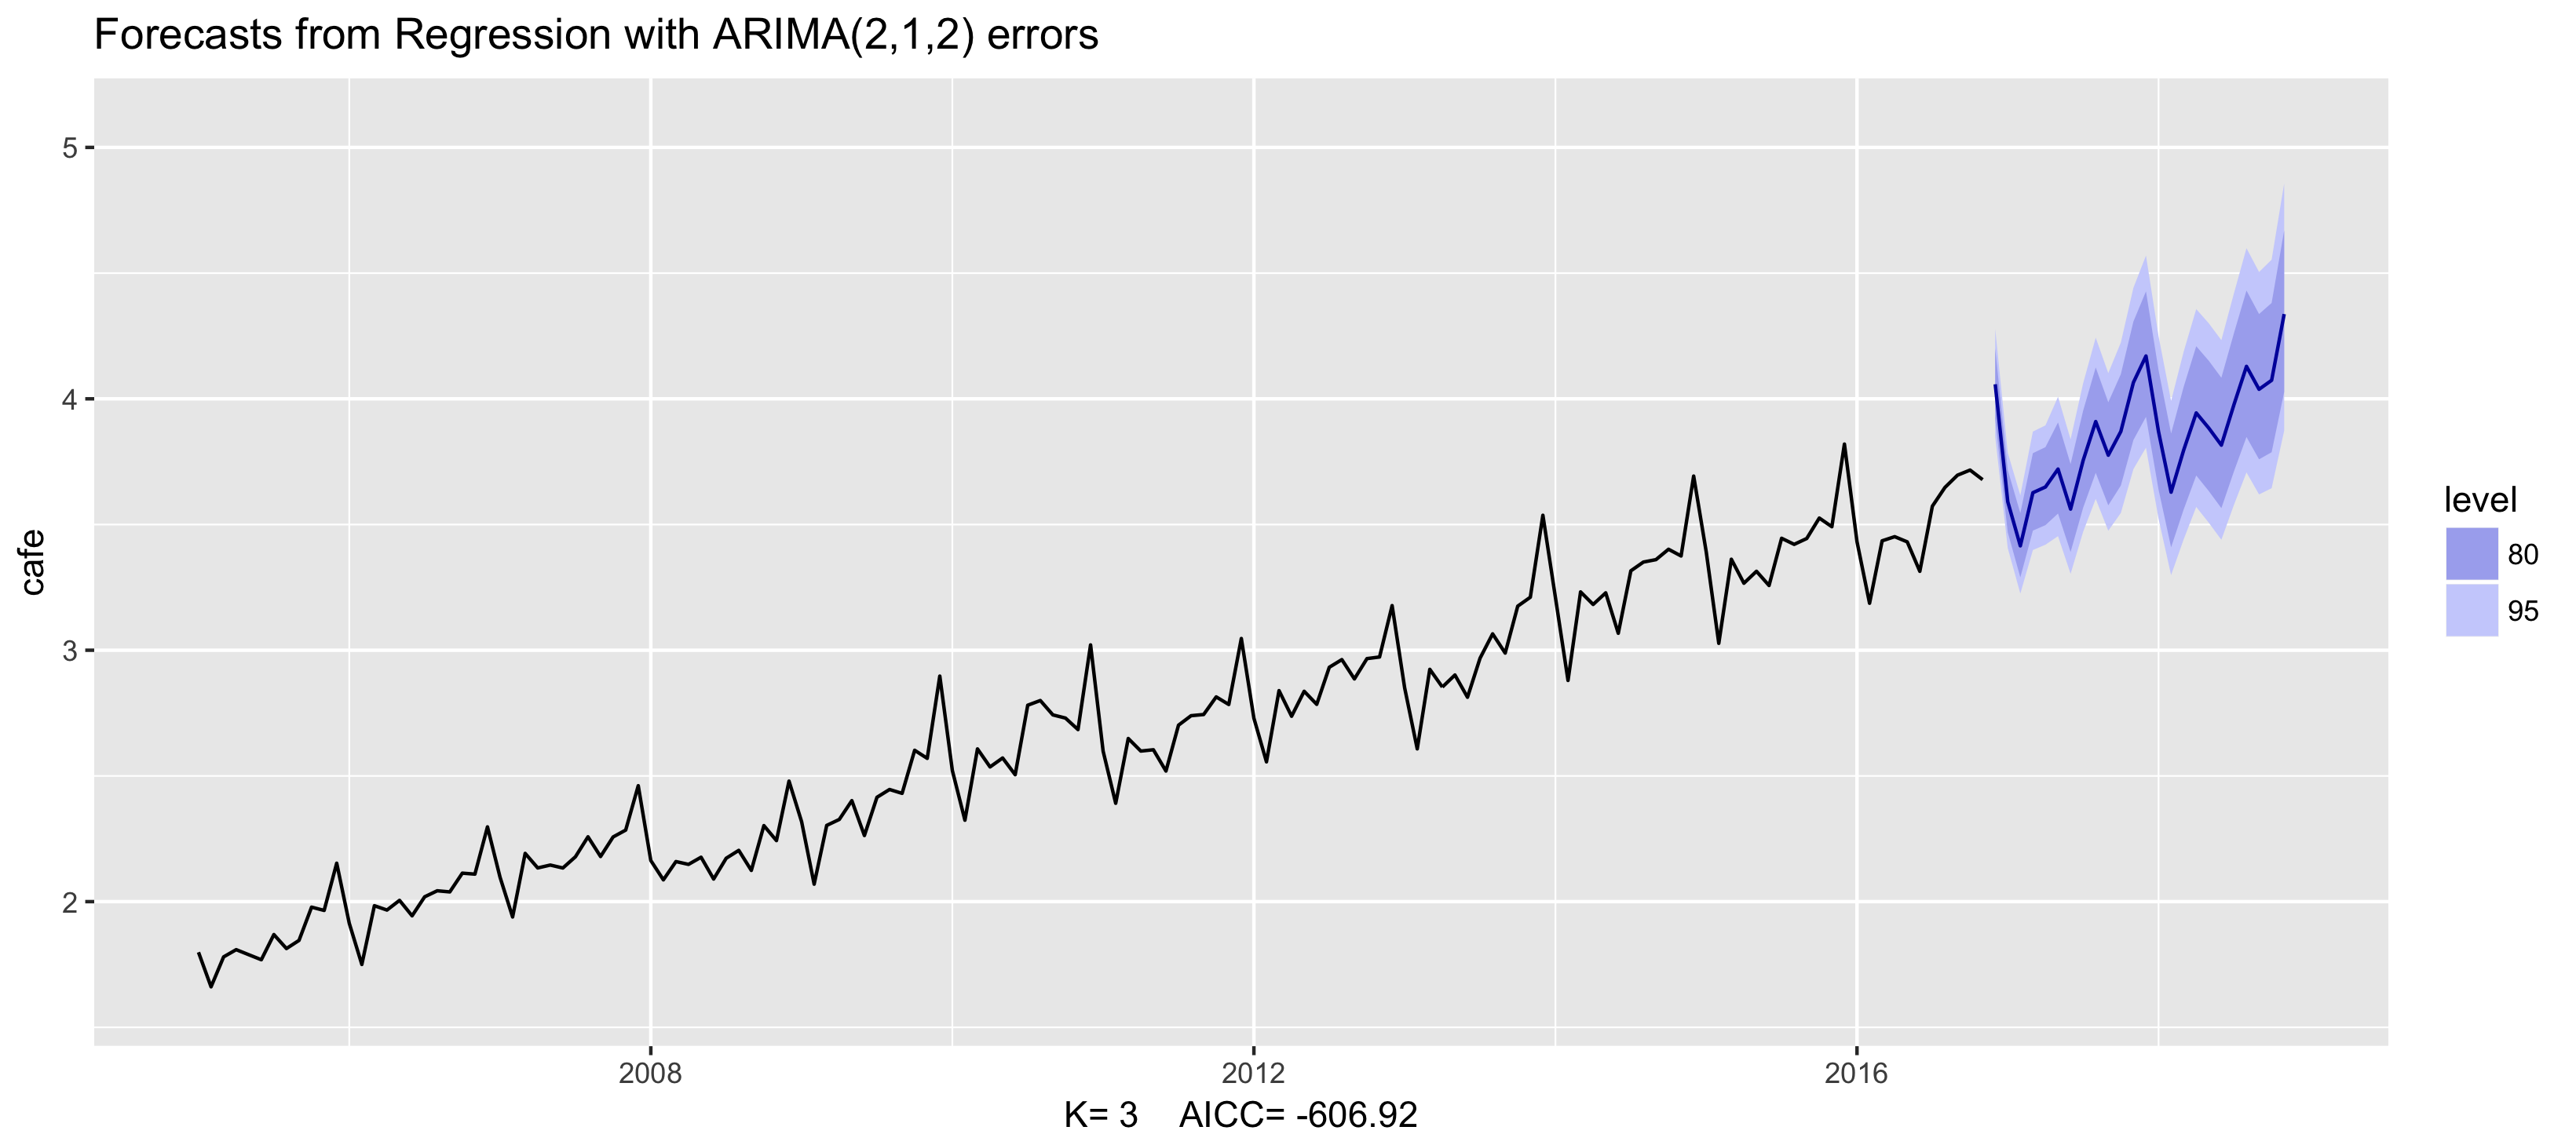
範例:澳洲咖啡館支出
fit <- auto.arima(cafe, xreg = fourier(cafe, K = 4),
                  seasonal = FALSE, lambda = 0)
fit %>% forecast(xreg = fourier(cafe, K = 4, h = 24)) %>%
   autoplot() + ylim(1.6, 5.1)
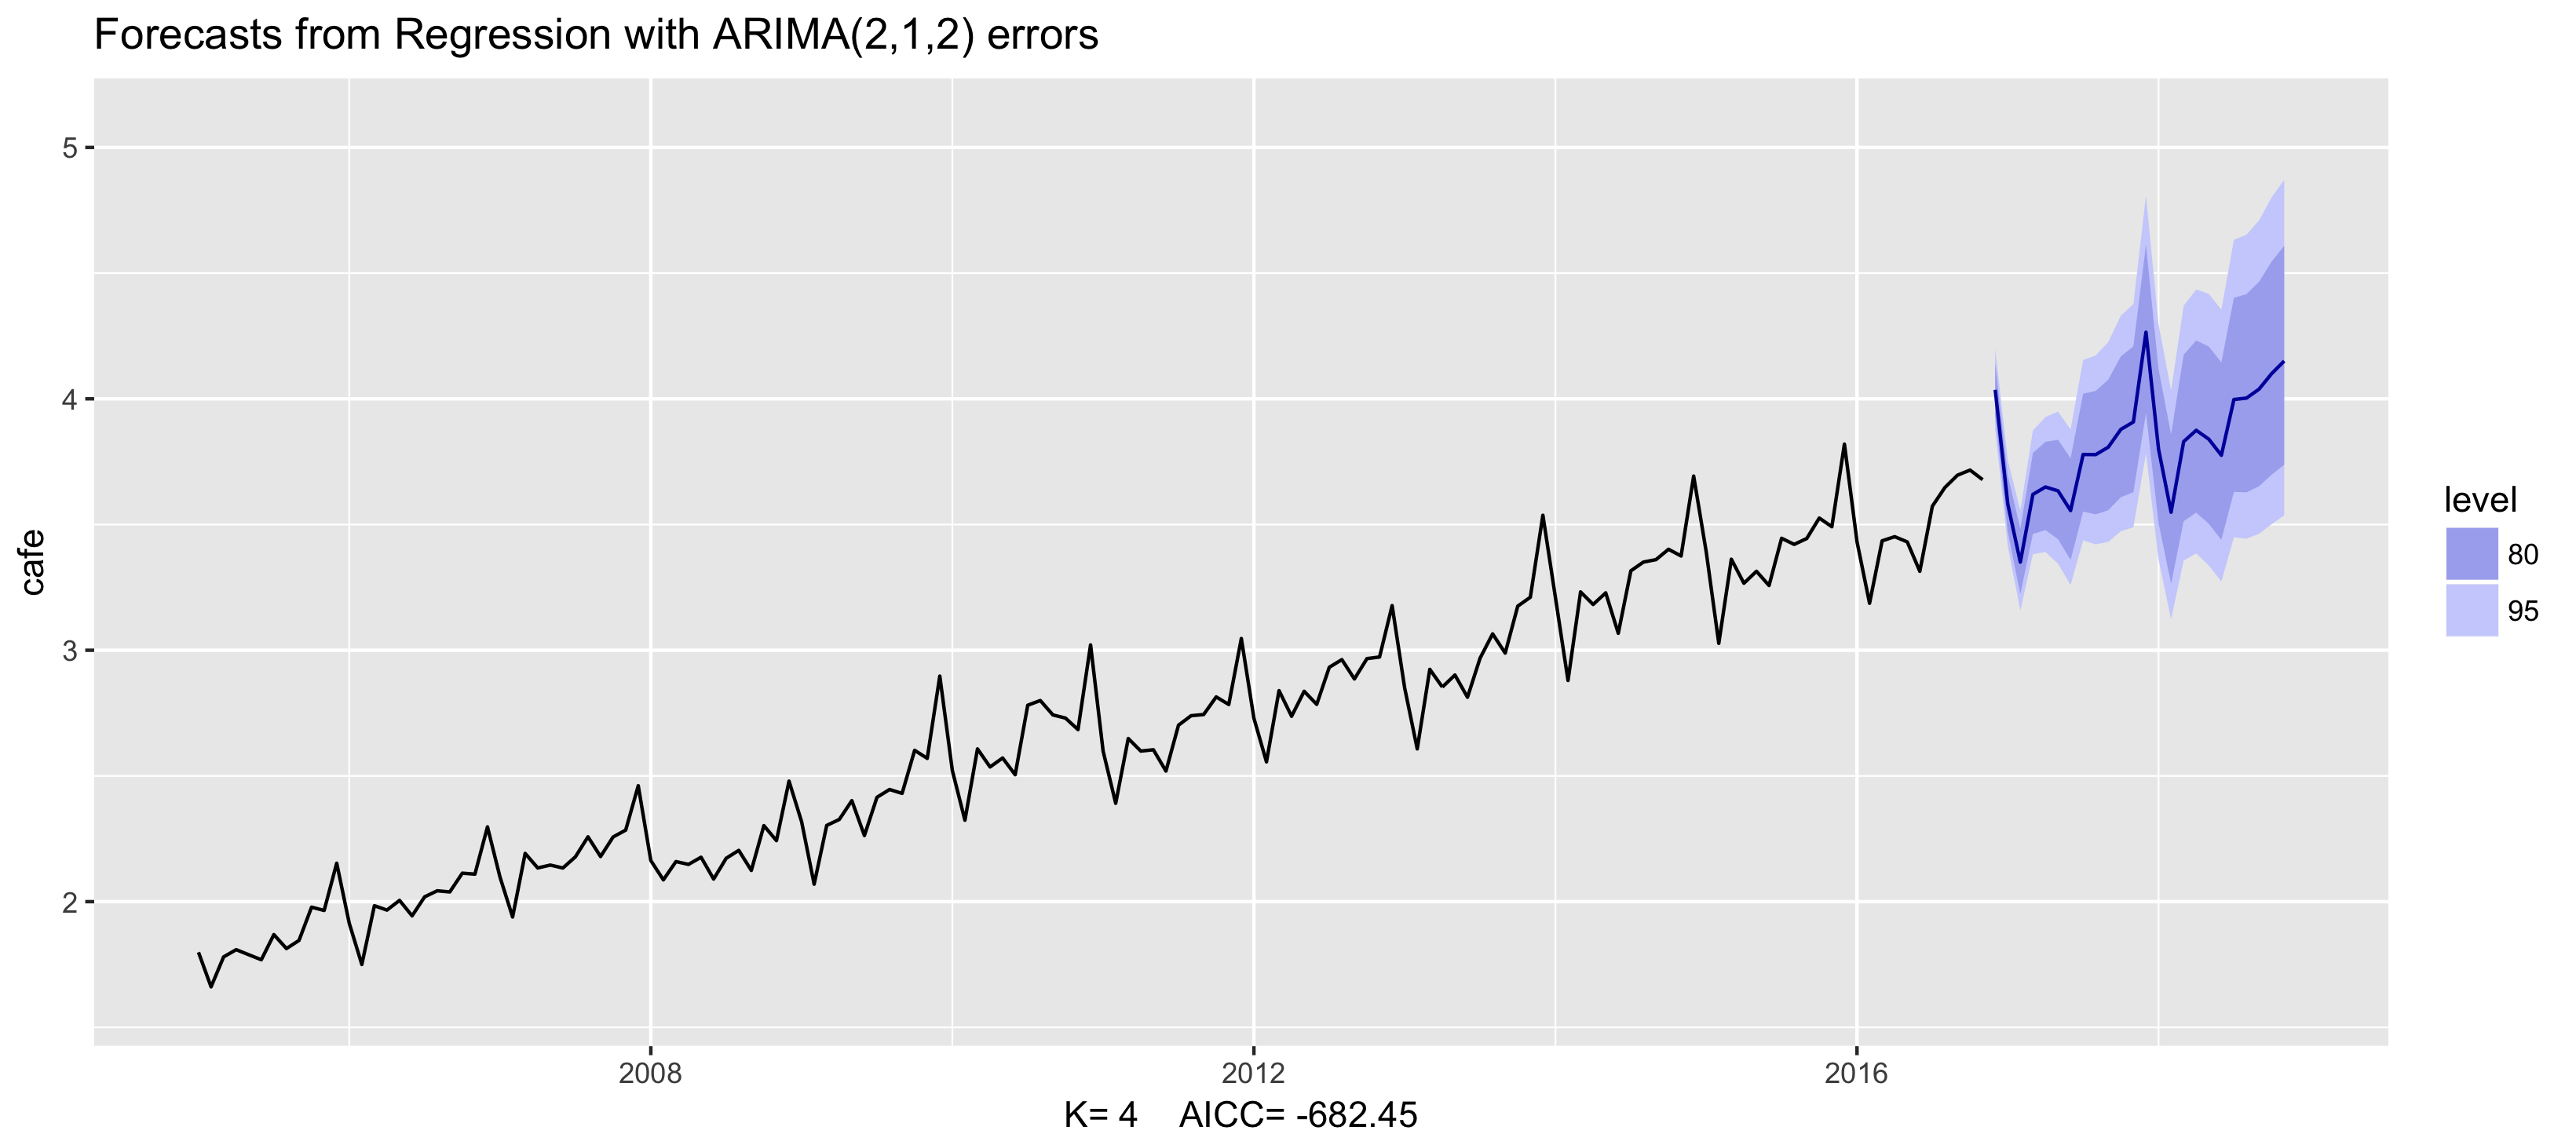
範例:澳洲咖啡館支出
fit <- auto.arima(cafe, xreg = fourier(cafe, K = 5),
                  seasonal = FALSE, lambda = 0)
fit %>% forecast(xreg = fourier(cafe, K = 5, h = 24)) %>%
   autoplot() + ylim(1.6, 5.1)
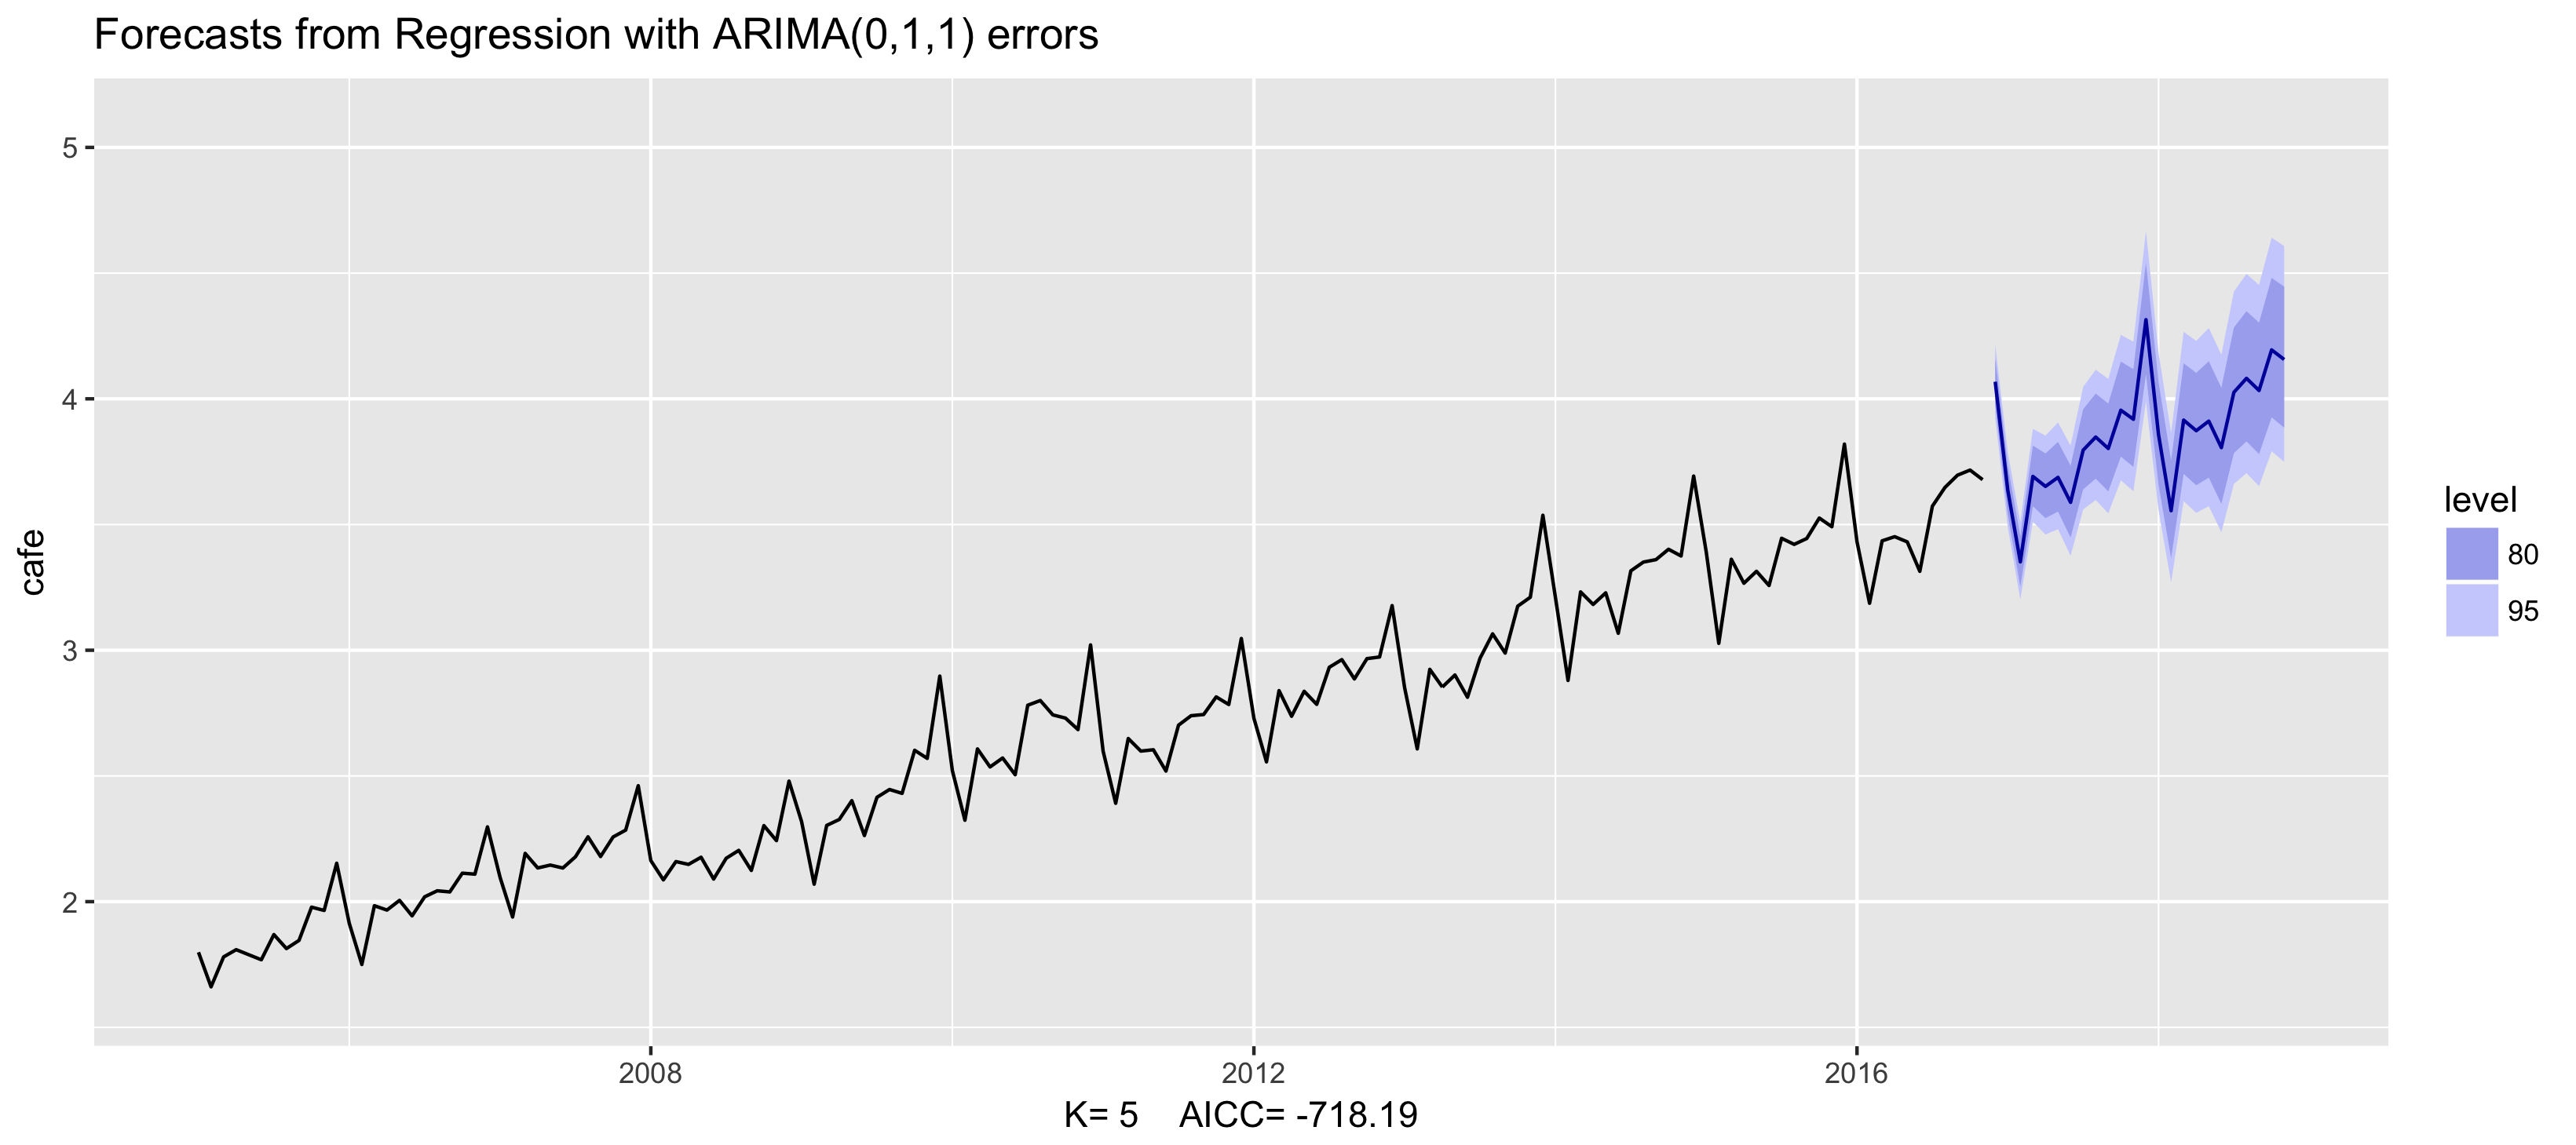
範例:澳洲咖啡館支出
fit <- auto.arima(cafe, xreg = fourier(cafe, K = 6),
                  seasonal = FALSE, lambda = 0)
fit %>% forecast(xreg = fourier(cafe, K = 6, h = 24)) %>%
   autoplot() + ylim(1.6, 5.1)
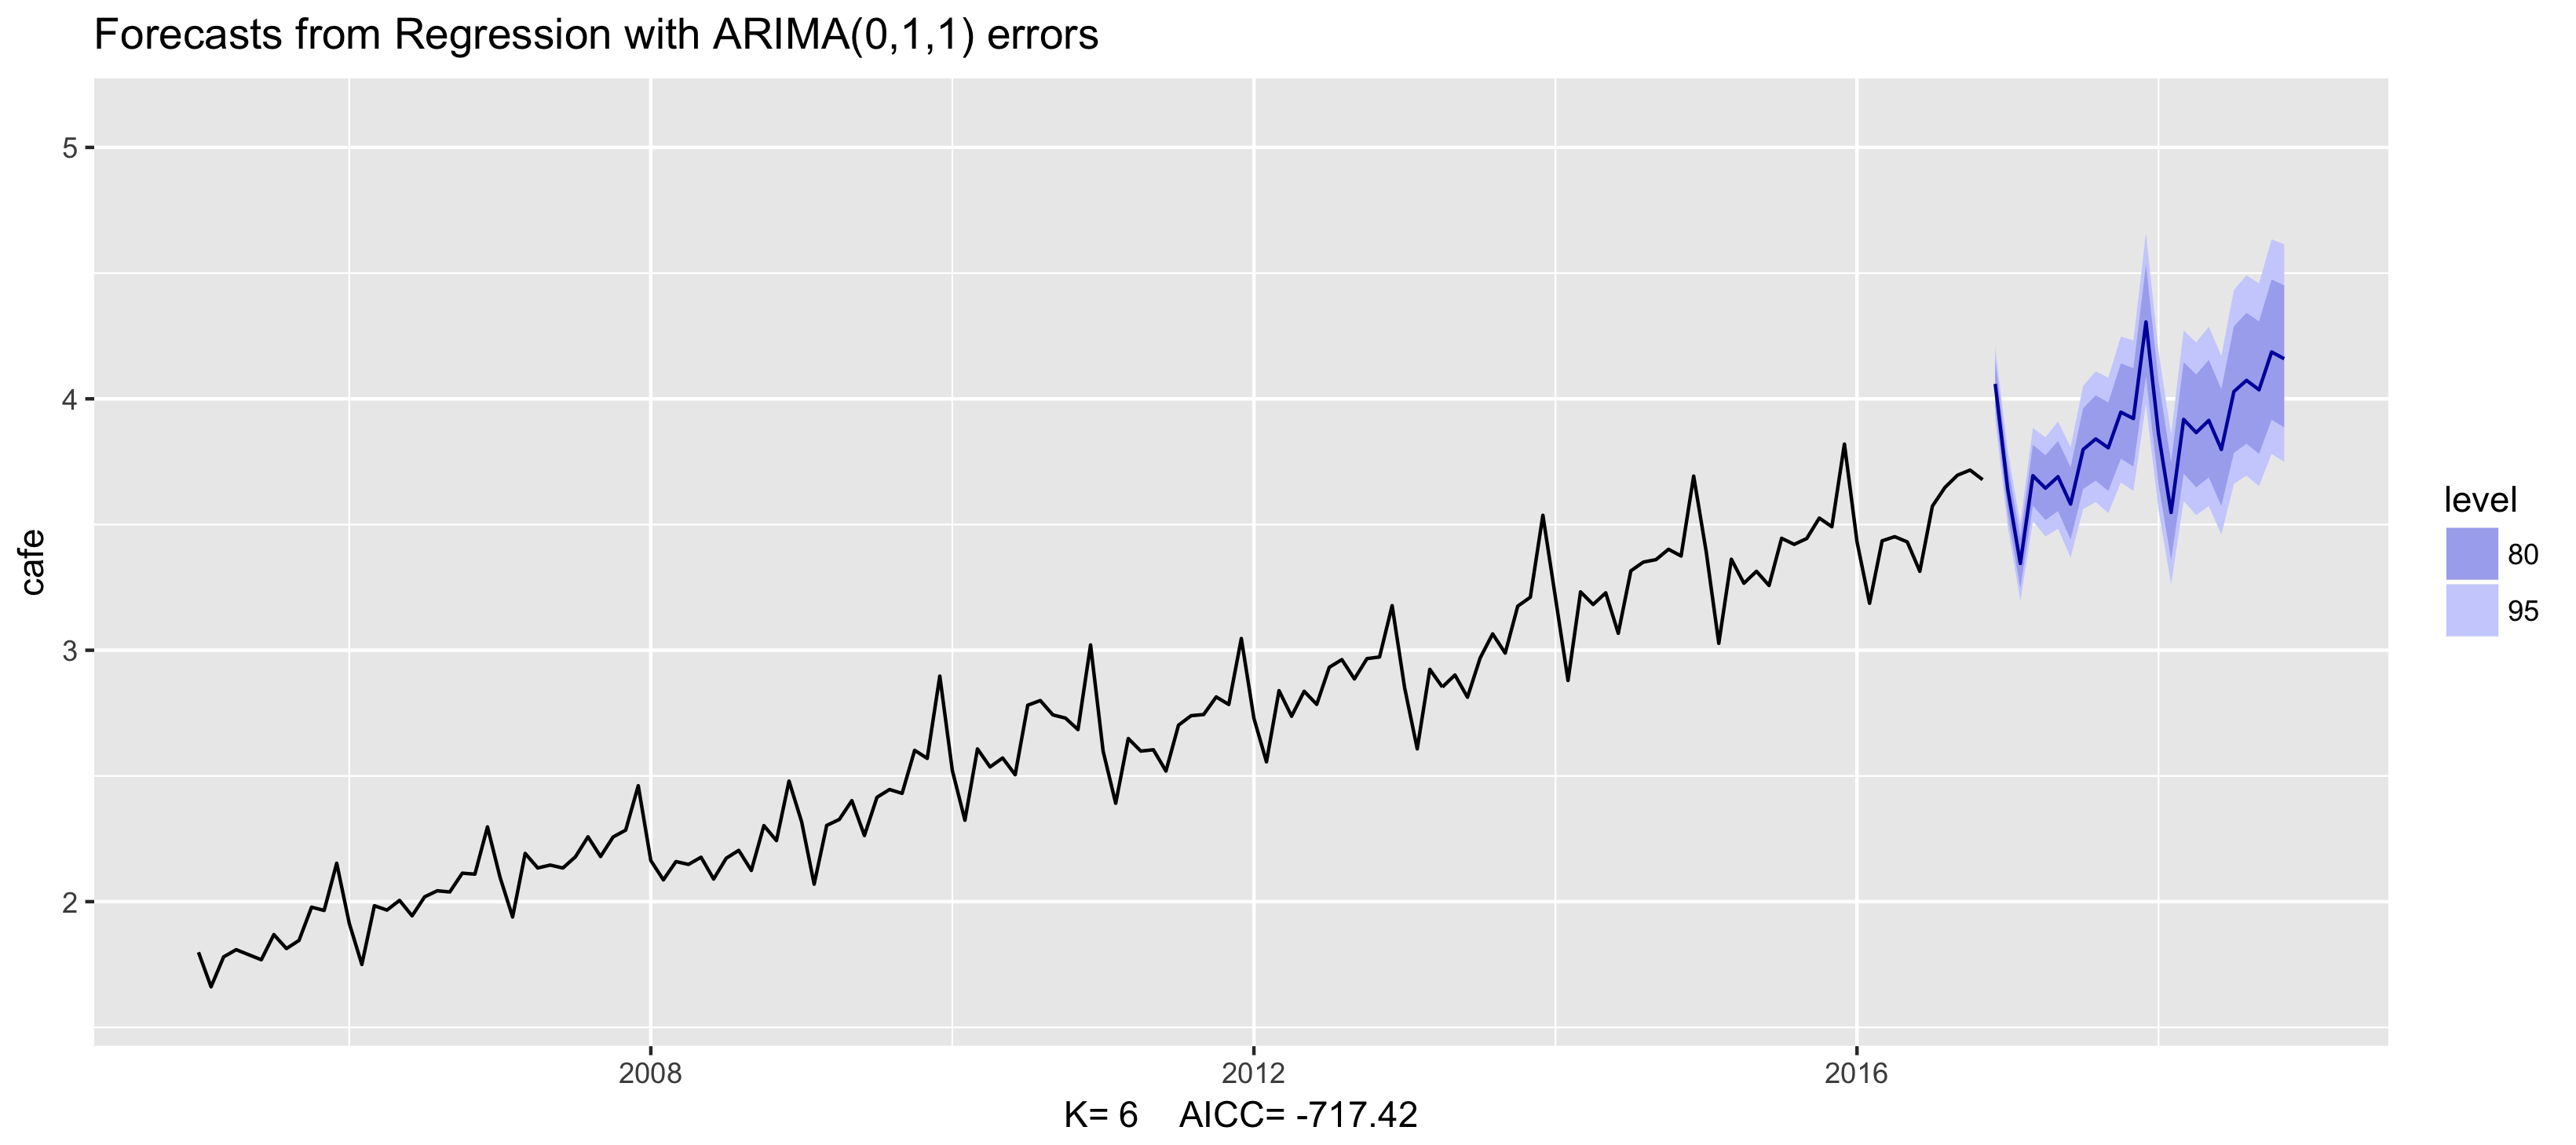
動態諧波迴歸
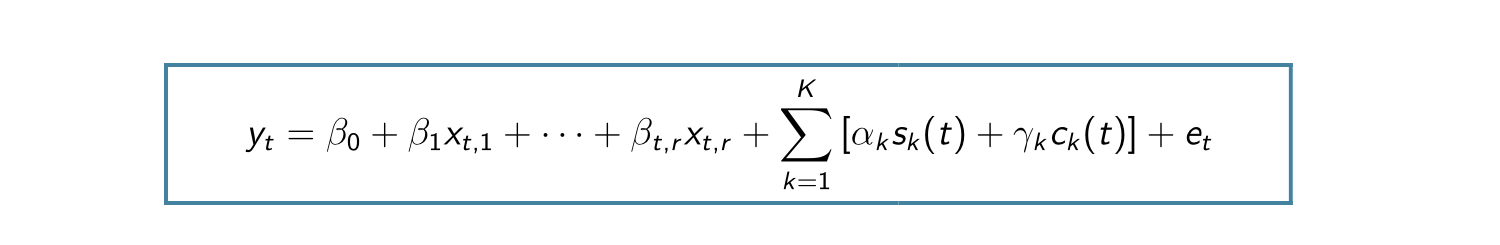
- 也可加入其他解釋變數:$x_{t,1},...,x_{t,r}$
- 選擇 K 使 $AIC_c$ 最小
- K 不可超過 m/2
- 對每週、每日與次日資料特別實用

