ARIMA 預測
R 中的 ARIMA 模型

David Stoffer
Professor of Statistics at the University of Pittsburgh
ARIMA 過程的預測
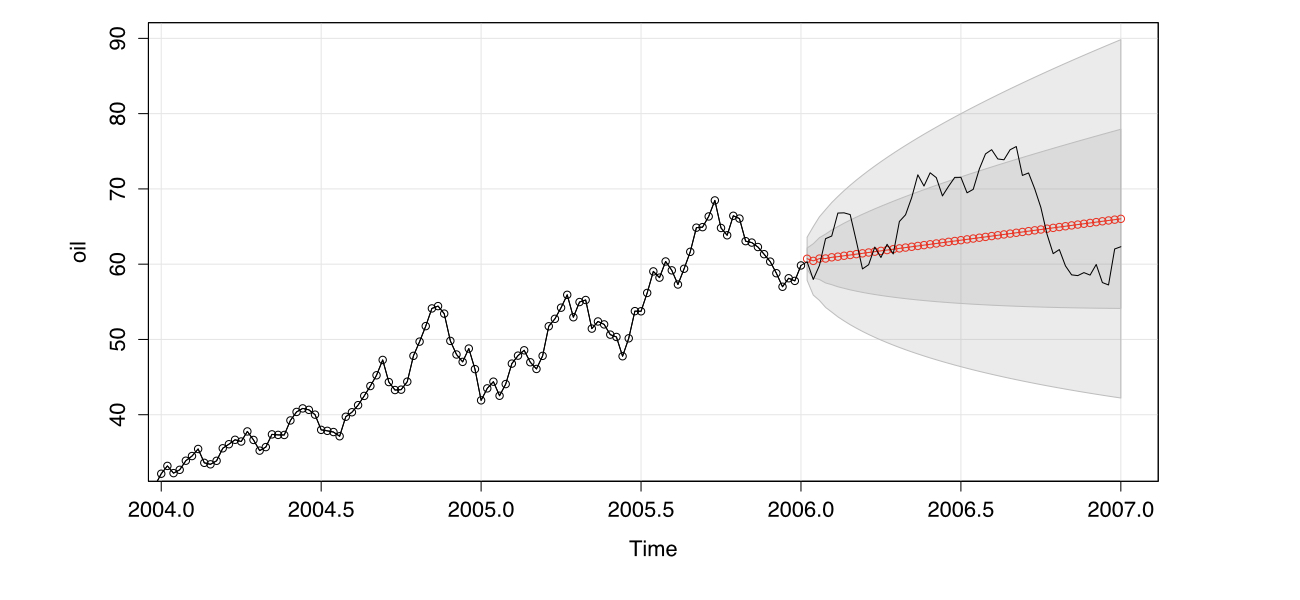
oil <- window(astsa::oil, end = 2006) oilf <- window(astsa::oil, end = 2007) sarima.for(oil, n.ahead = 52, 1, 1, 1)lines(oilf)
R 中的 ARIMA 模型
David Stoffer
Professor of Statistics at the University of Pittsburgh
oil <- window(astsa::oil, end = 2006) oilf <- window(astsa::oil, end = 2007) sarima.for(oil, n.ahead = 52, 1, 1, 1)lines(oilf)

