Python 中的 GARCH 模型
Chelsea Yang
Data Science Instructor
from arch import arch_model

用三步驟建立 GARCH 模型:
模型假設:
"normal"(預設)、"t"、"skewt""constant"(預設)、"zero"、"AR""GARCH"(預設)、"ARCH"、"EGARCH"
basic_gm = arch_model(sp_data['Return'], p = 1, q = 1,
mean = 'constant', vol = 'GARCH', dist = 'normal')
每隔 n 次迭代顯示配適輸出:
gm_result = gm_model.fit(update_freq = 4)
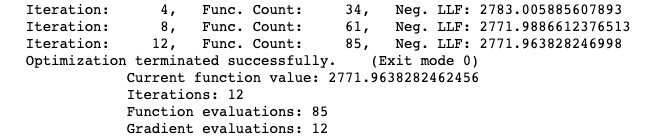
關閉顯示:
gm_result = gm_model.fit(disp = 'off')
以「極大概似法」估計。
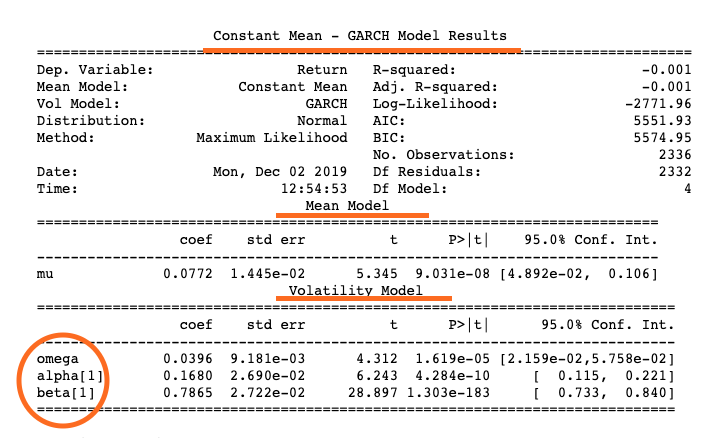
print(gm_result.params)
mu 0.077239
omega 0.039587
alpha[1] 0.167963
beta[1] 0.786467
Name: params, dtype: float64
print(gm_result.summary())

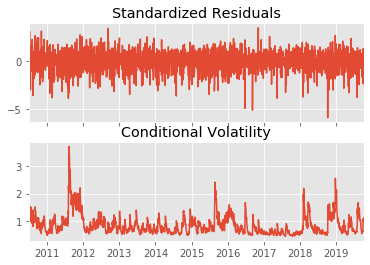
gm_result.plot()

# Make 5-period ahead forecast
gm_forecast = gm_result.forecast(horizon = 5)
# Print out the last row of variance forecast
print(gm_forecast.variance[-1:])
h.1 h.2 h.3 h.4 h.5
Date
2019-10-10 0.994079 0.988366 0.982913 0.977708 0.972741
列「2019-10-10」中的 h.1:使用該日期(含)之前資料做的 1 期前預測。
Python 中的 GARCH 模型