GARCH 滾動視窗預測
Python 中的 GARCH 模型

Chelsea Yang
Data Science Instructor
樣本外預測的滾動視窗
財務建模的精彩之處: 預測未知
滾動視窗預測: 隨著時間推進,重複配適模型並進行預測
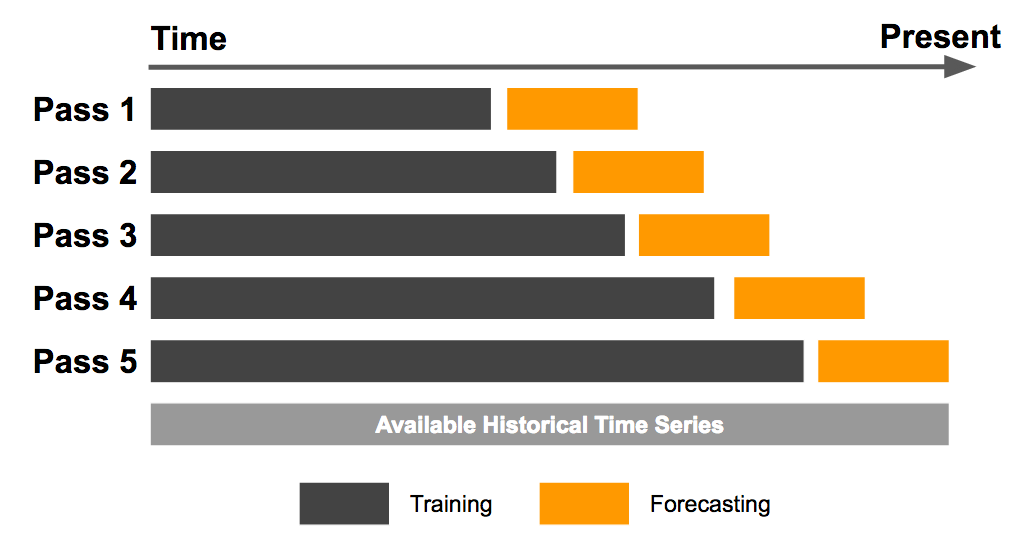
擴張視窗預測
持續將新資料點加入樣本
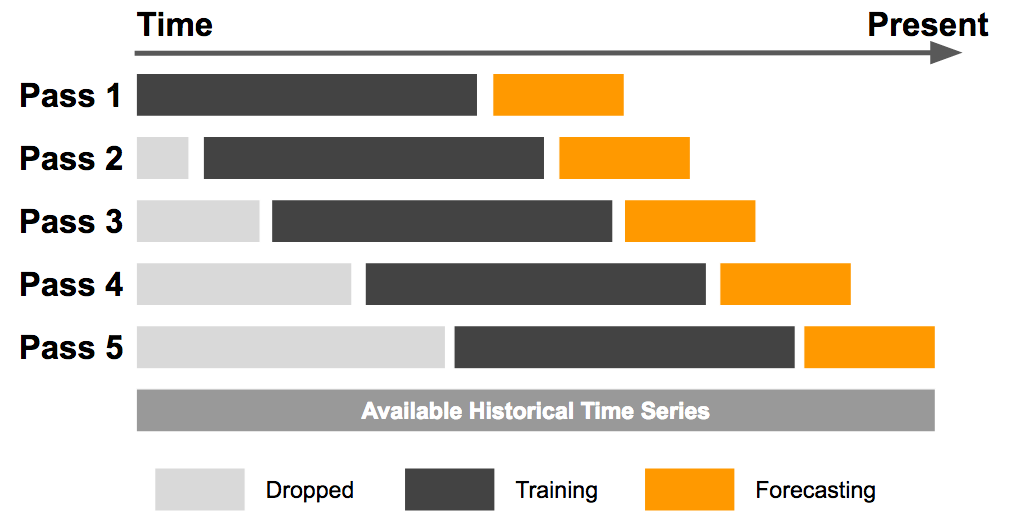
固定滾動視窗預測
加入新資料點,同時移除舊資料點
如何決定視窗大小
通常需視情況決定
視窗太大:納入過時資料,可能提高變異數
視窗太小:排除相關資料,可能提高偏誤
最佳視窗大小:在偏誤與變異數間取捨
Python 中的 GARCH 模型
Chelsea Yang
Data Science Instructor
財務建模的精彩之處: 預測未知
滾動視窗預測: 隨著時間推進,重複配適模型並進行預測
持續將新資料點加入樣本
加入新資料點,同時移除舊資料點
通常需視情況決定
視窗太大:納入過時資料,可能提高變異數
視窗太小:排除相關資料,可能提高偏誤
最佳視窗大小:在偏誤與變異數間取捨

