白噪音(WN)模型
R 的時間序列分析

David S. Matteson
Associate Professor at Cornell University
白噪音
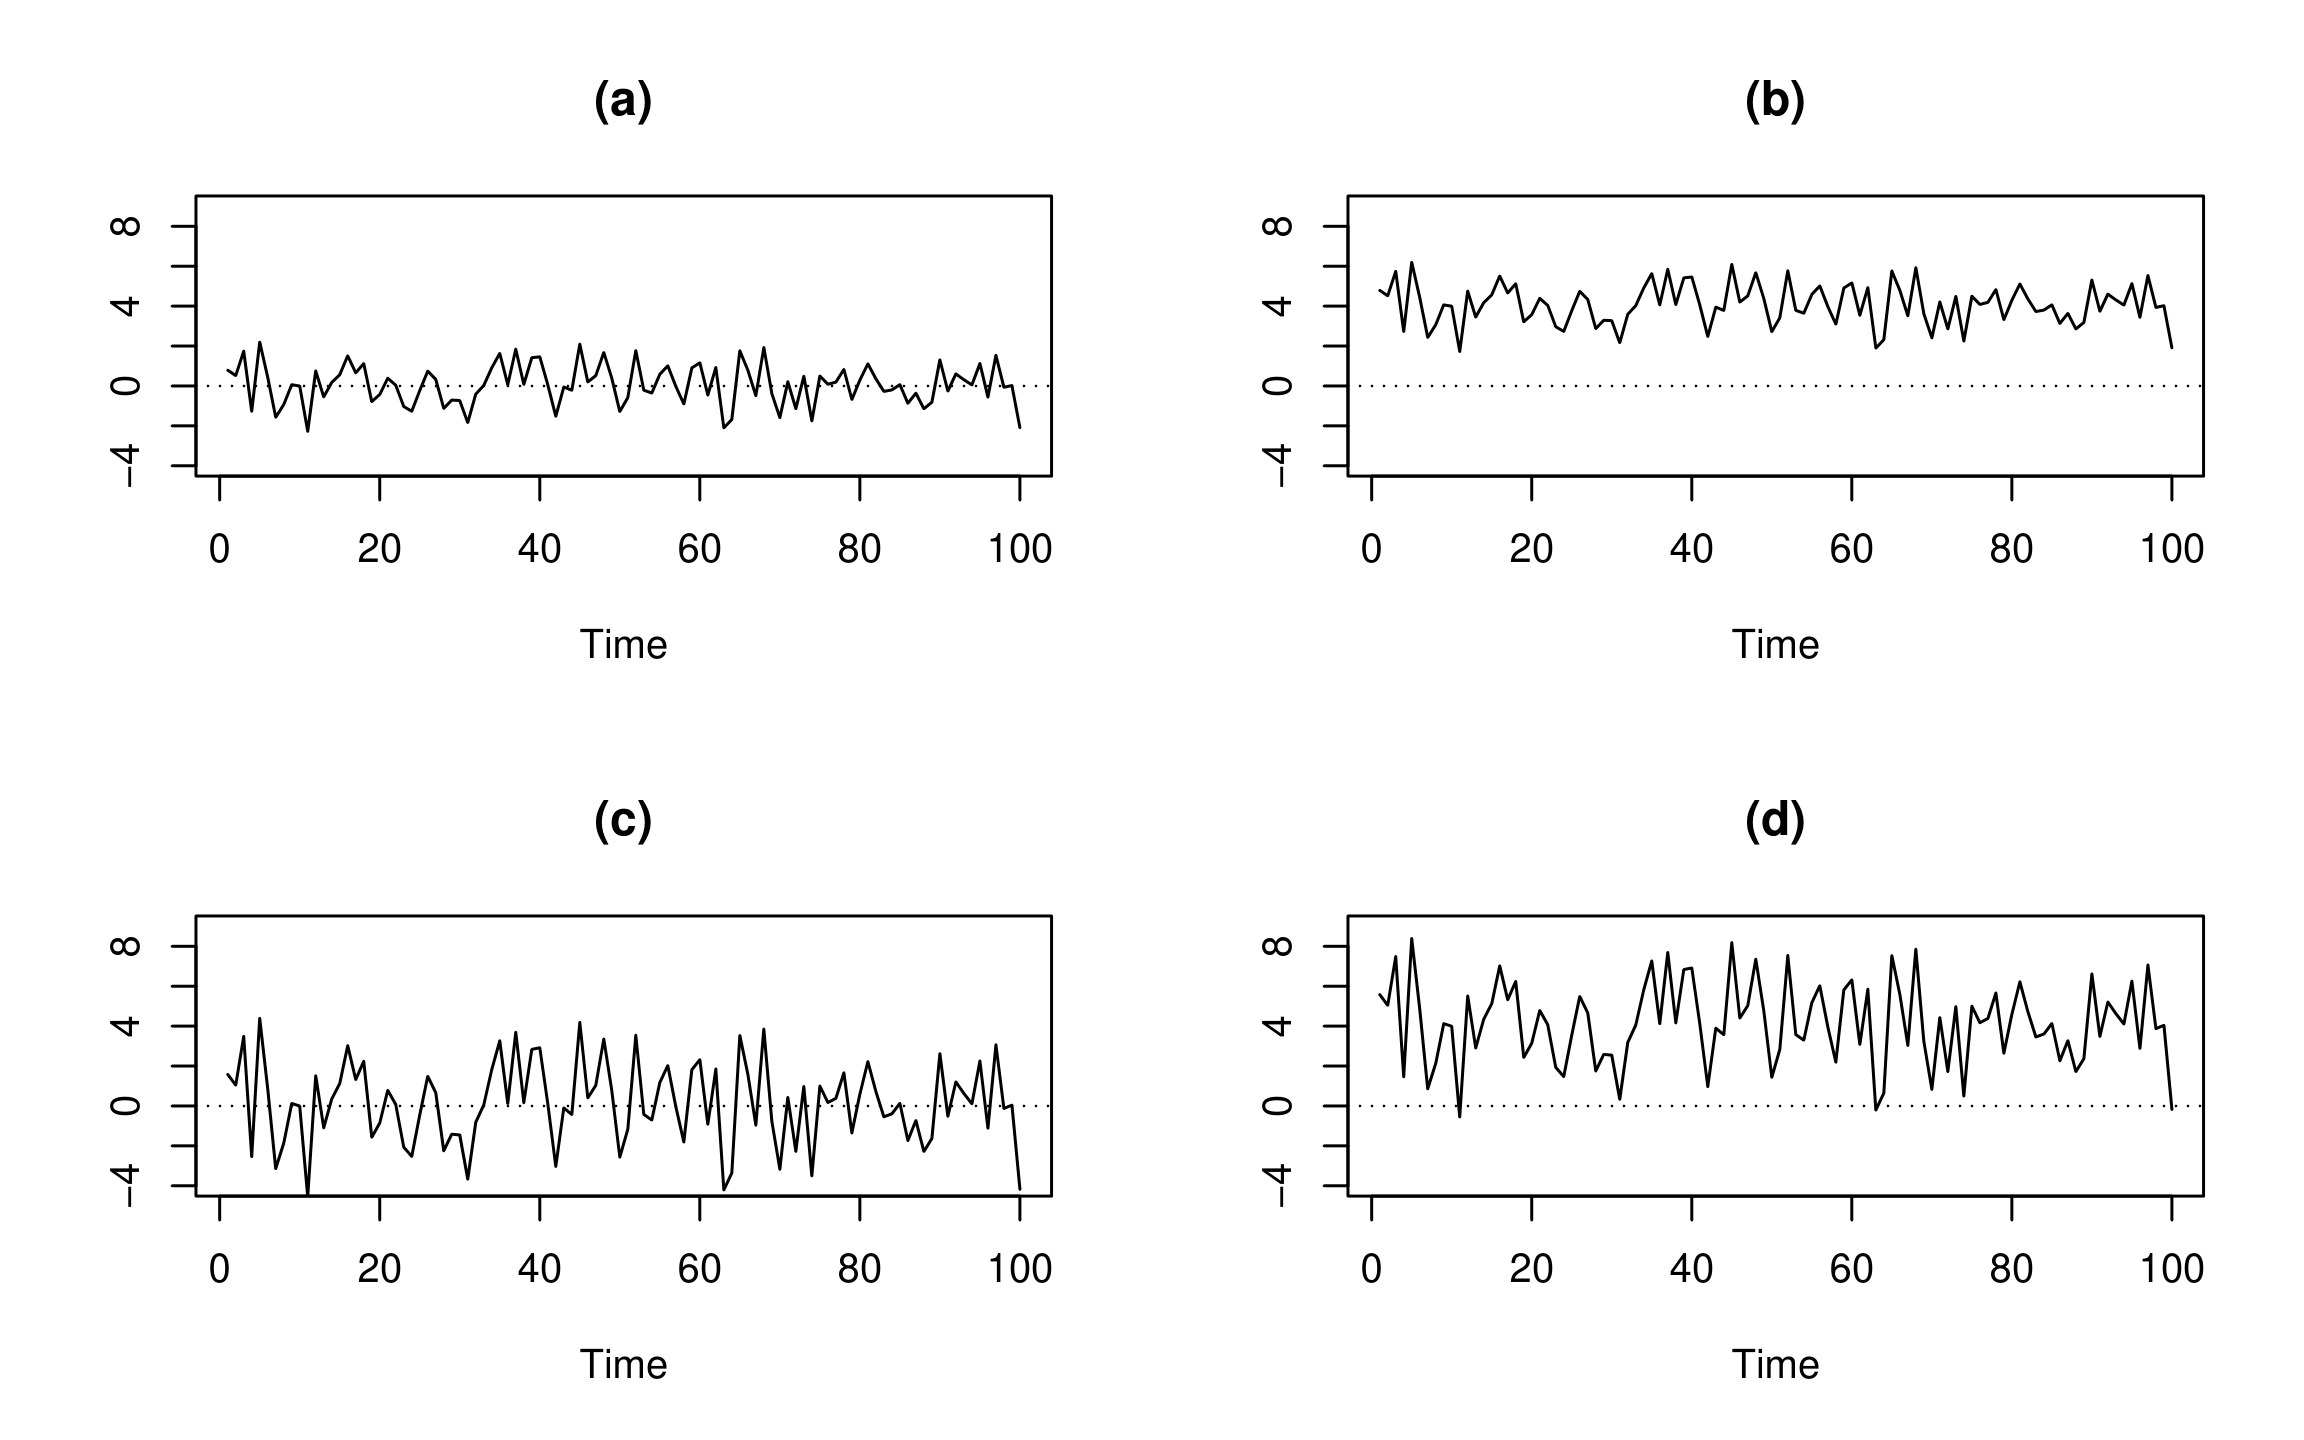
白噪音的時間序列圖:
白噪音
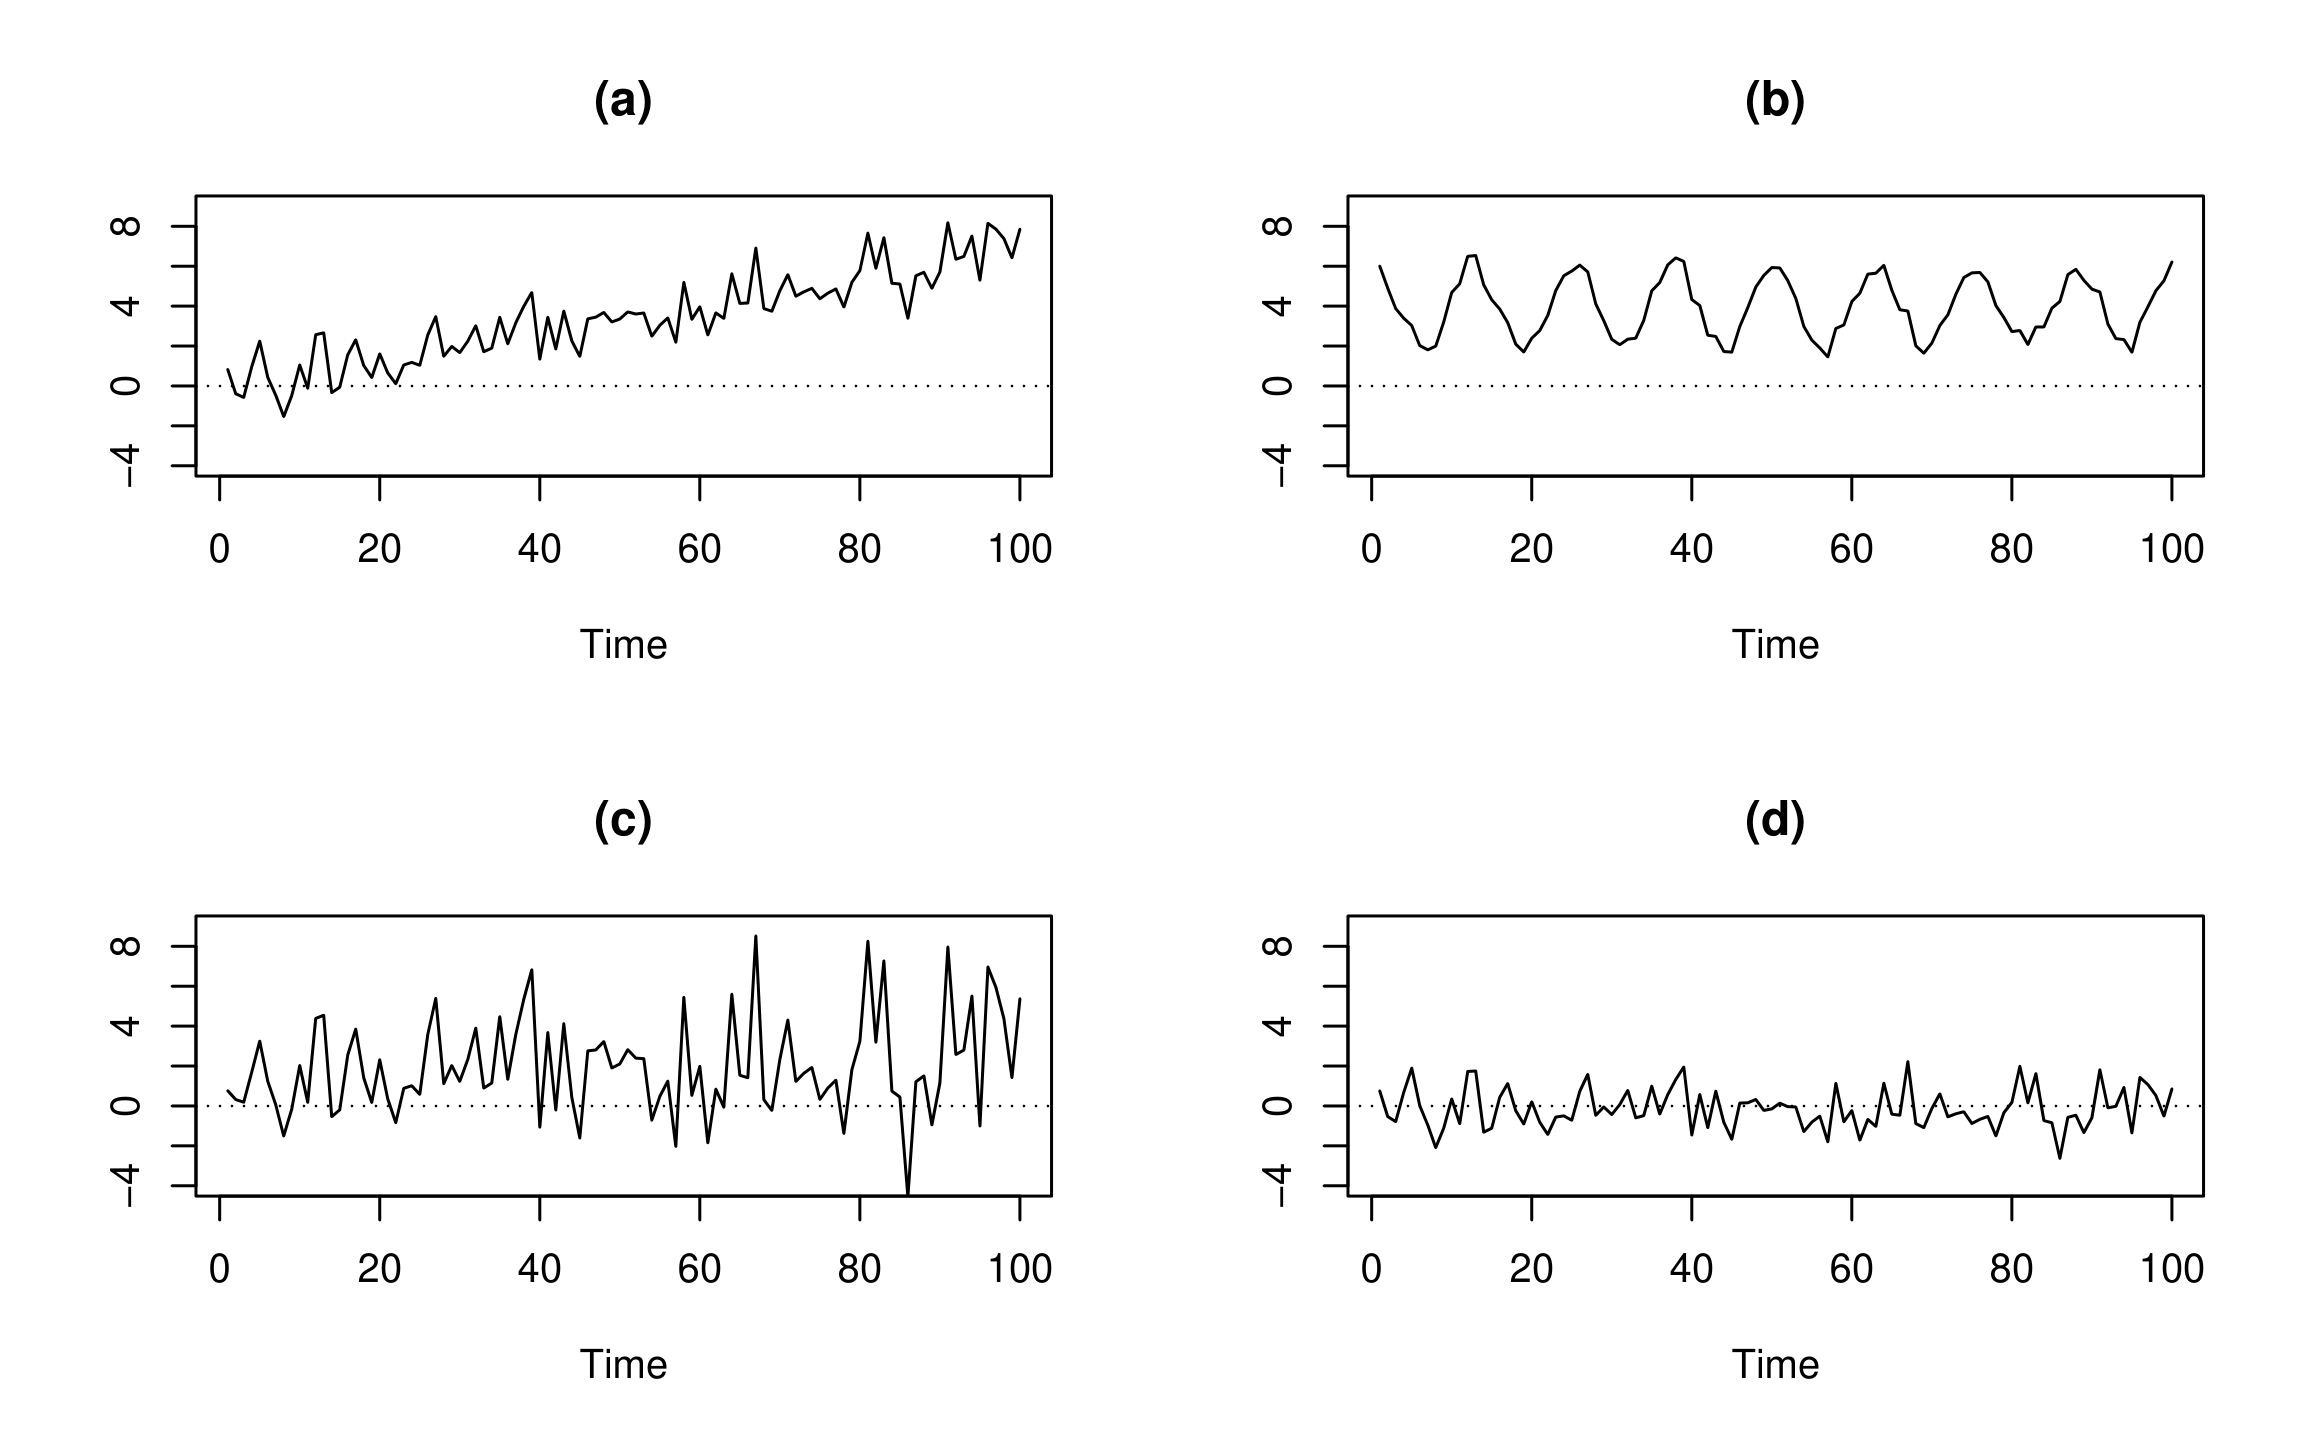
這也是白噪音的時間序列圖嗎?
# Simulate n = 50 observations from the WN model
WN_1 <- arima.sim(model = list(order = c(0, 0, 0)), n = 50)
head(WN_1)
-0.005052984  0.042669765  3.261154066
 2.486431235  0.283119322  1.543525773
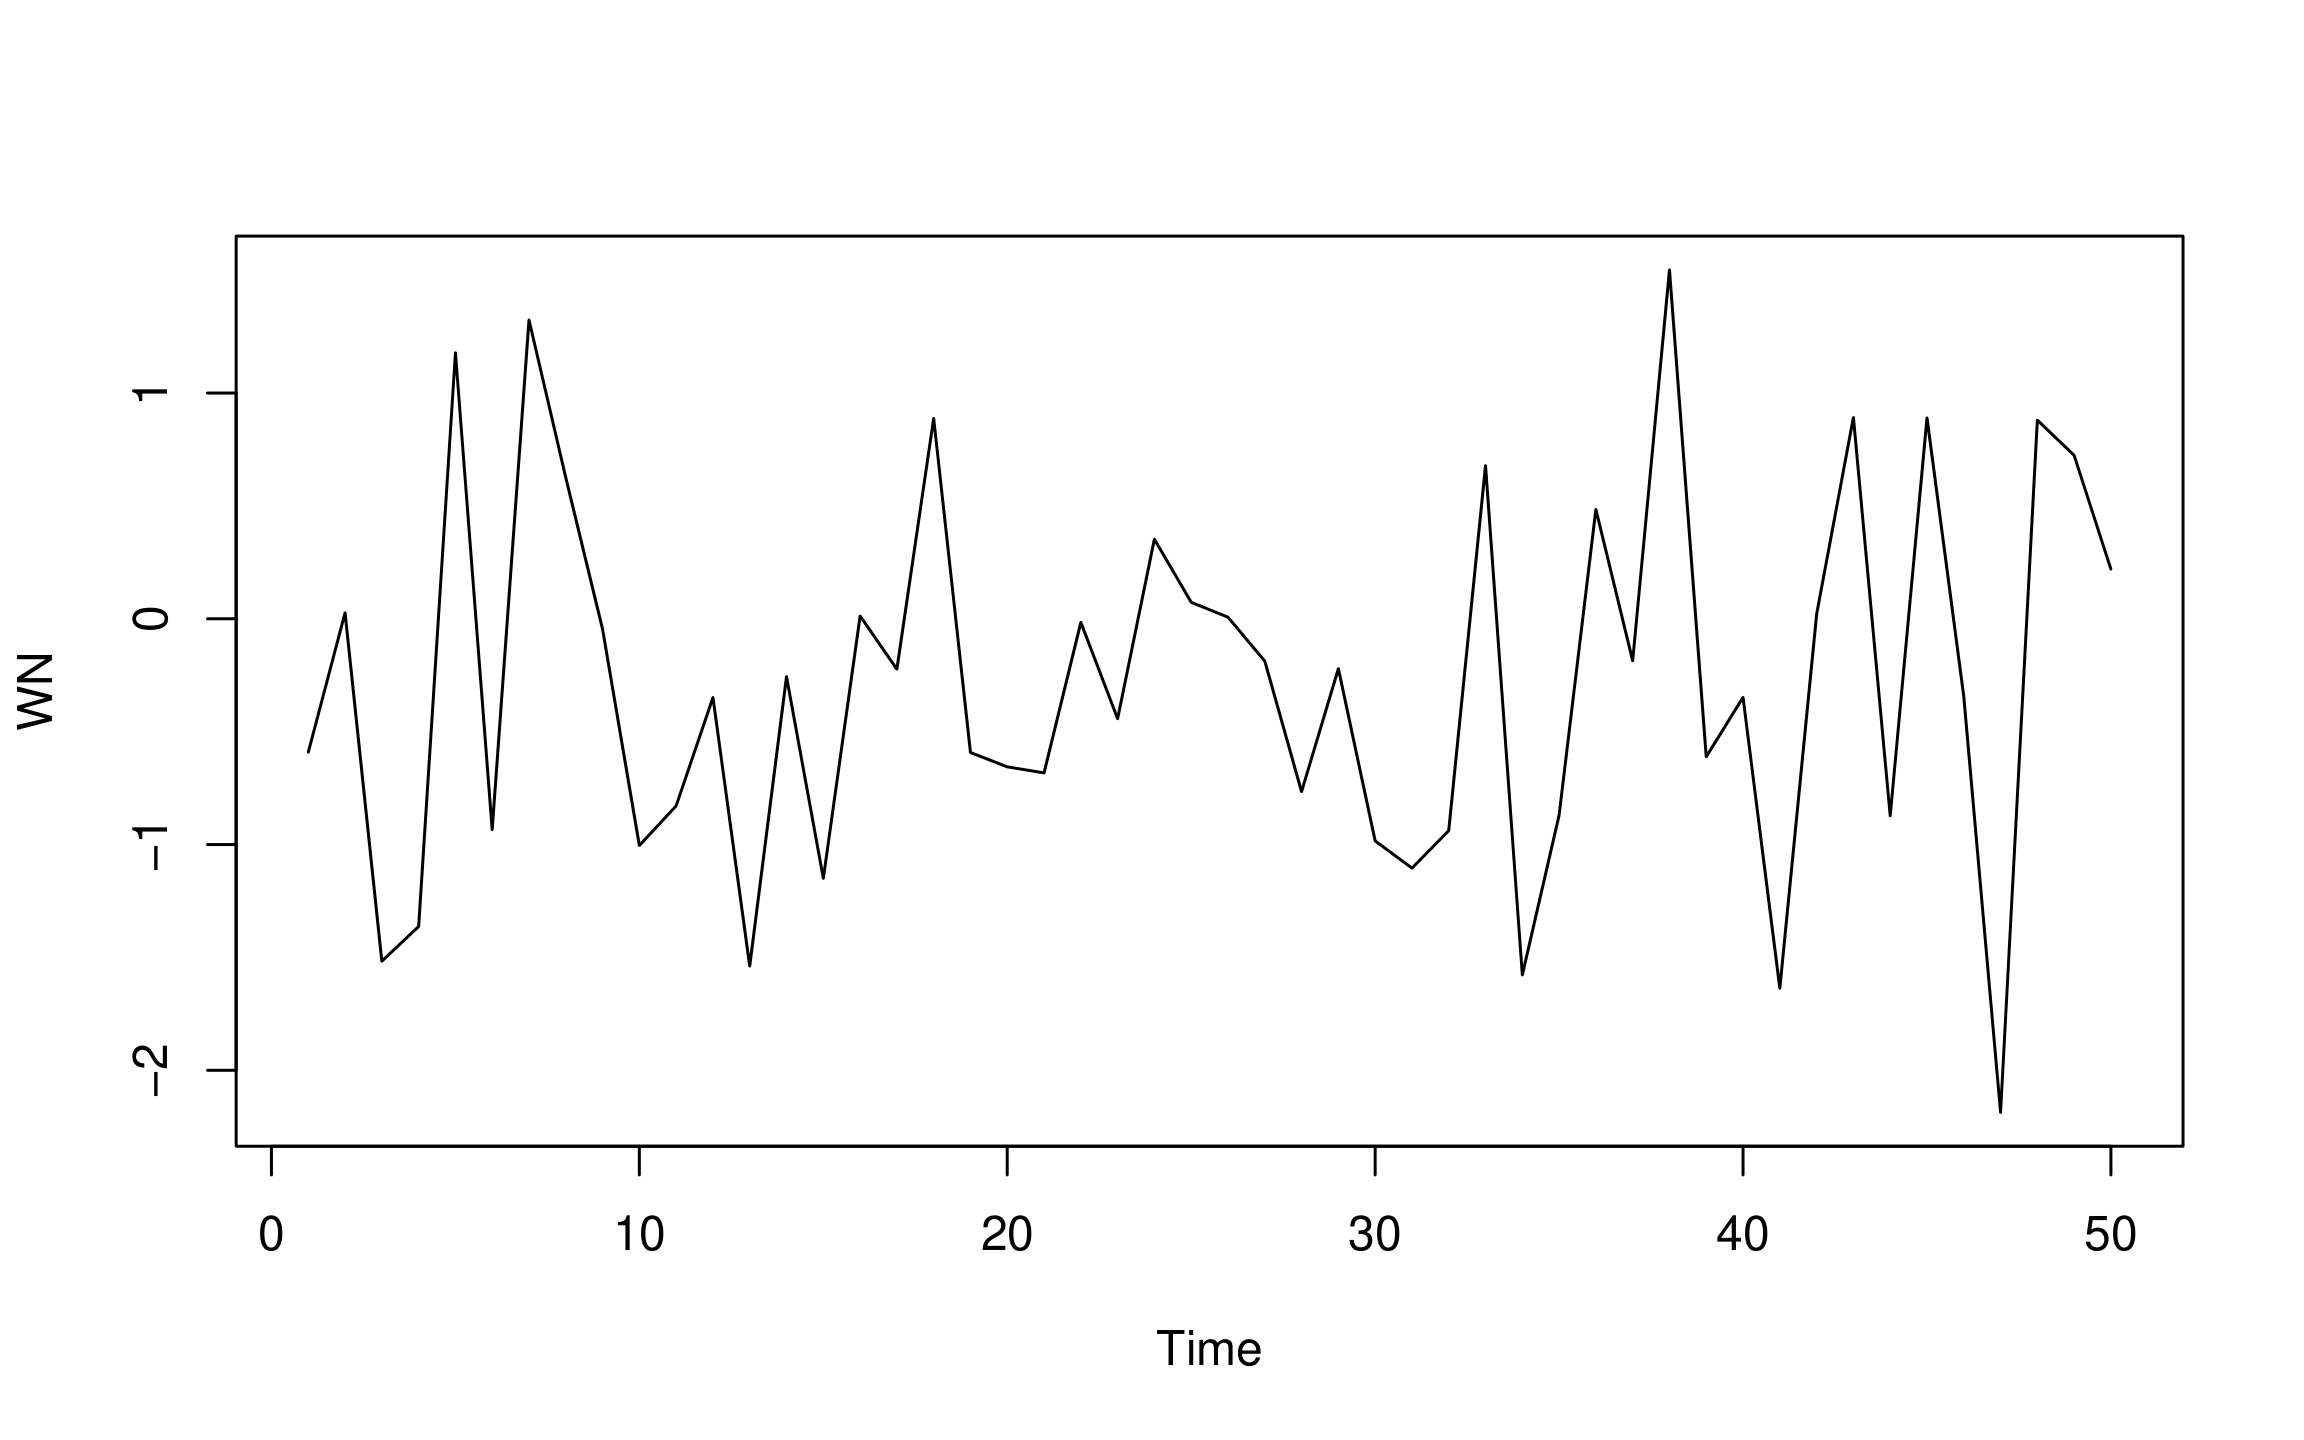
ts.plot(WN_1)
# Simulate from the WN model with mean = 4, sd = 2
WN_2 <- arima.sim(model = list(order = c(0, 0, 0)),
                  n = 50, mean = 4, sd = 2)
ts.plot(WN_2)

