簡單移動平均模型
R 的時間序列分析

David S. Matteson
Associate Professor at Cornell University
簡單移動平均模型
簡單移動平均(MA)模型:
$ Today = Mean + Noise + Slope * (Yesterday's Noise)$
更正式地: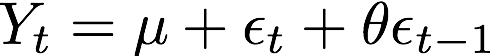
其中 $ \epsilon_t$ 為均值為 0 的白雜訊(WN)。
三個參數:
- 均值 $\mu$
- 斜率 $\theta$
- WN 變異數 $\sigma^2$
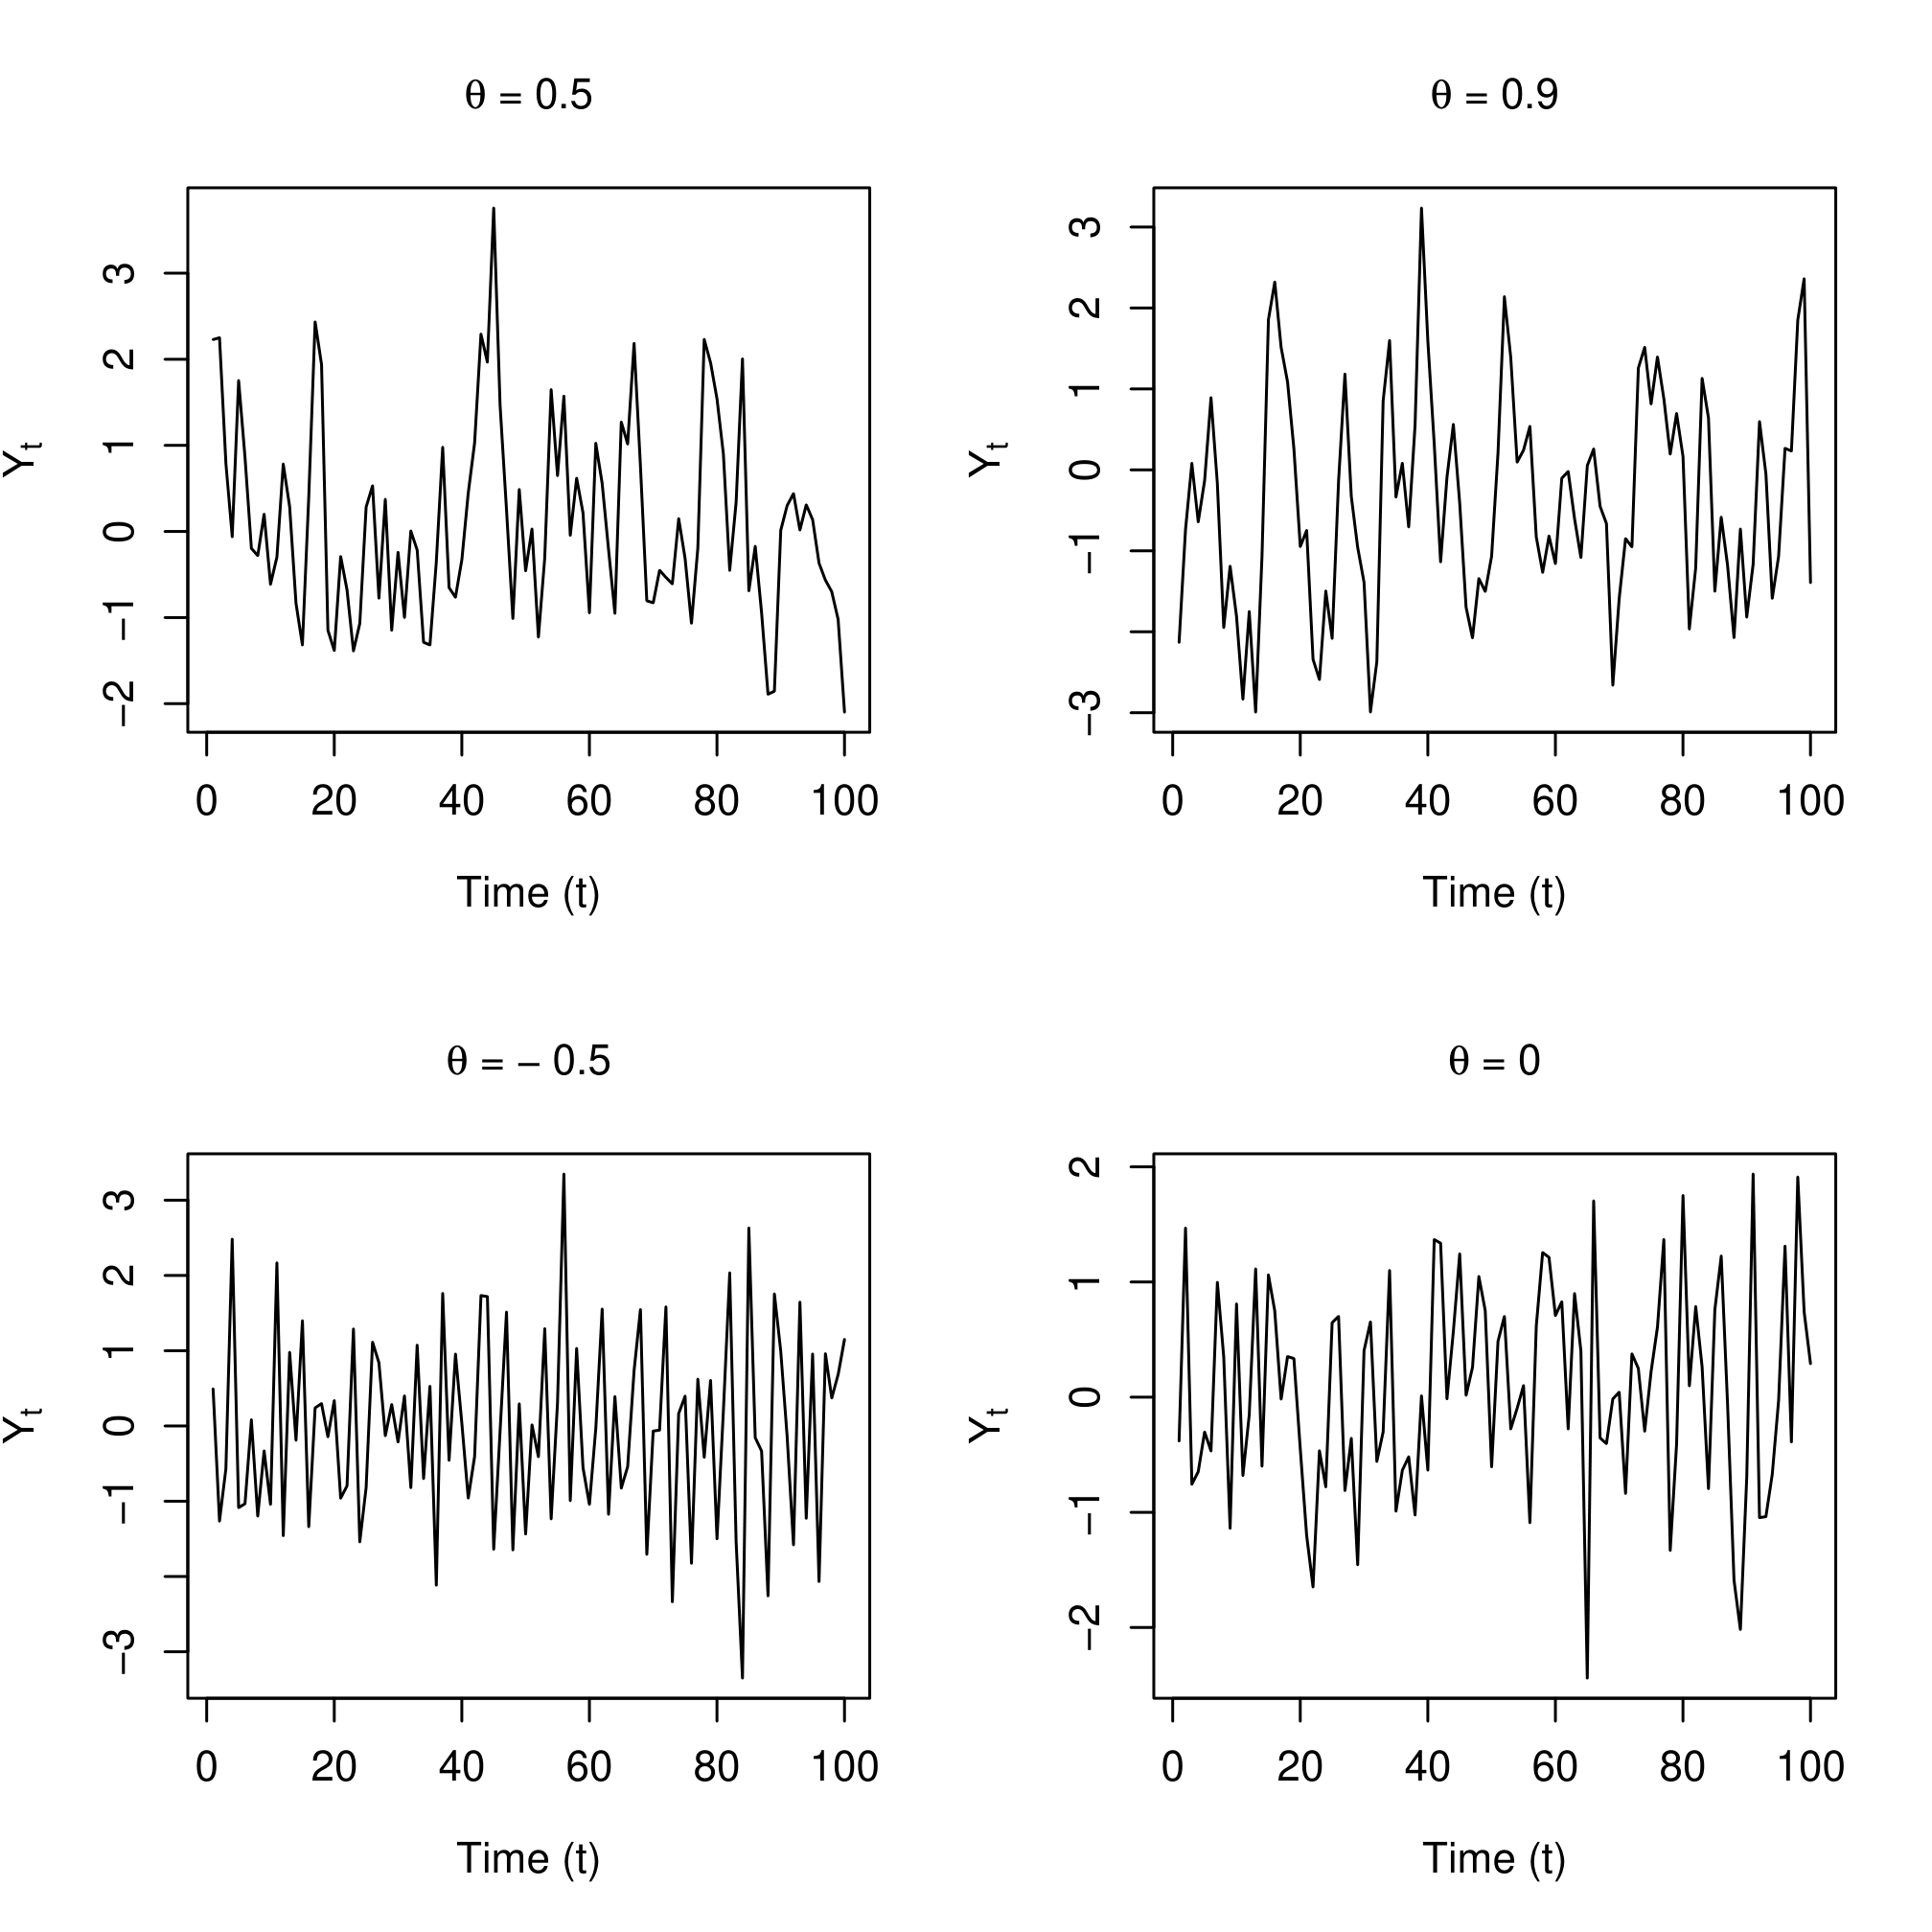
MA 範例
自我相關
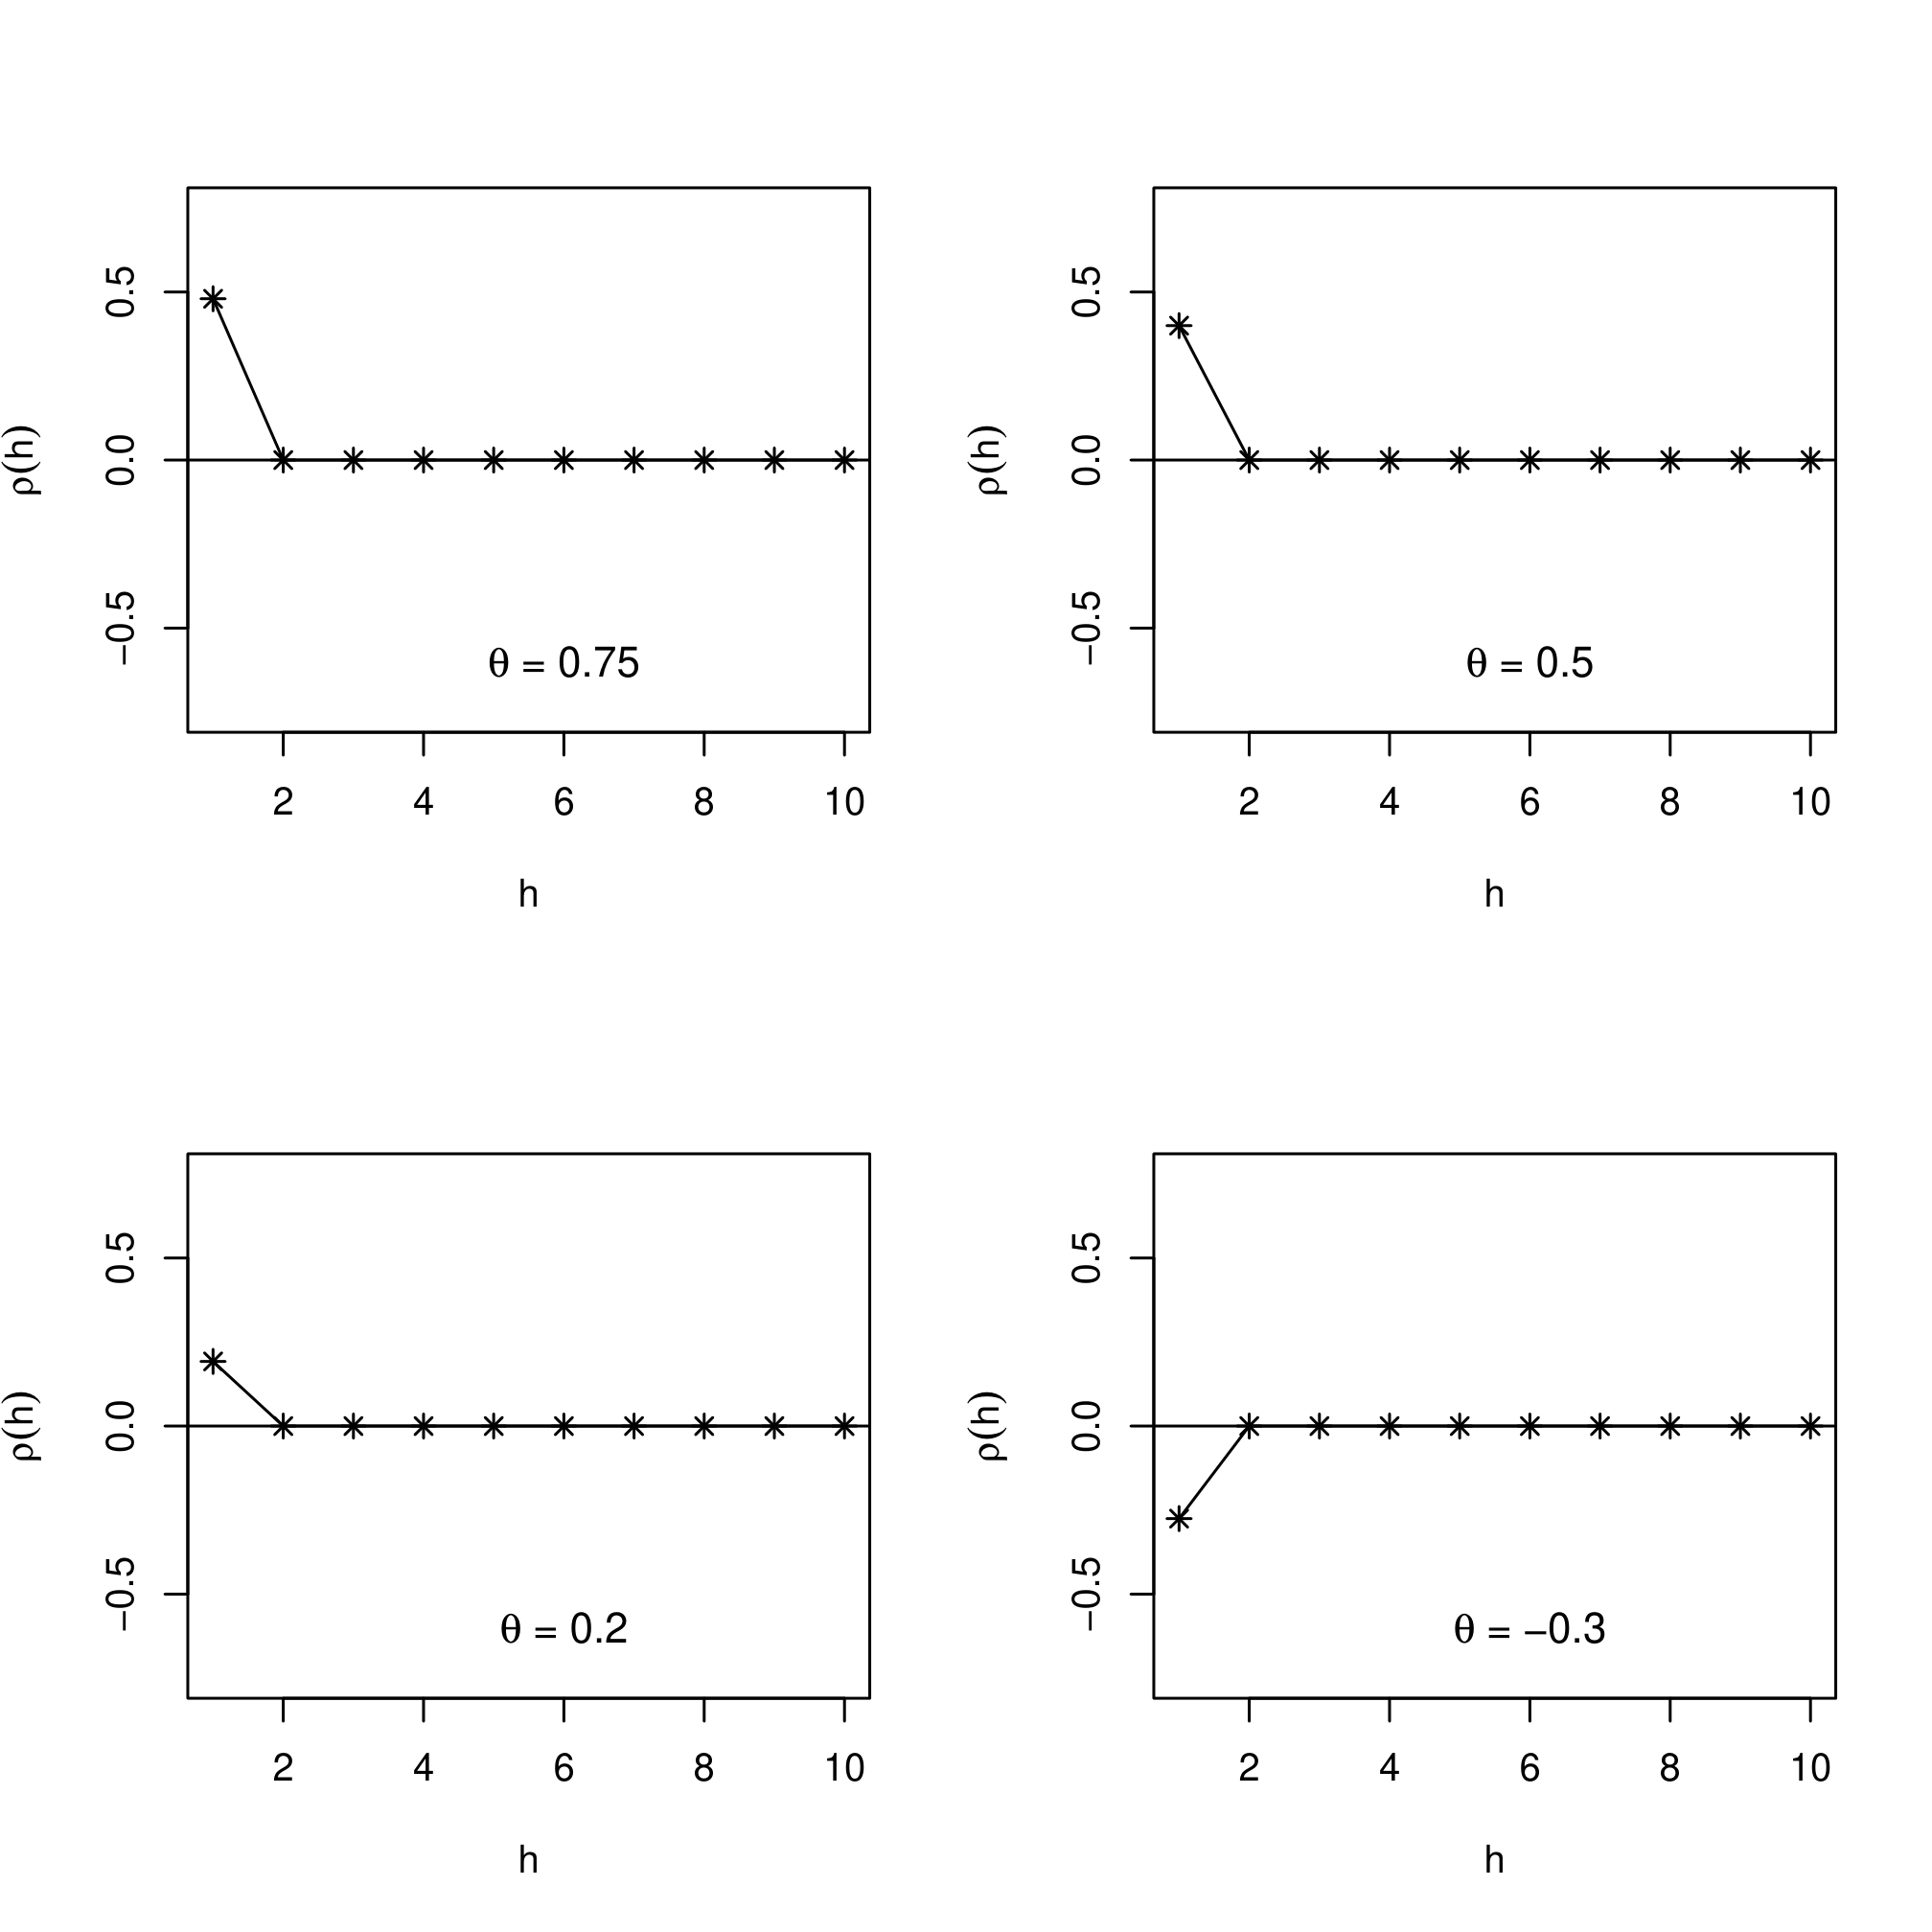
對 MA 模型,只有落後 1 的自我相關不為 0。

