不吃苦,難有收穫
R 的 GARCH 模型

Kris Boudt
Professor of finance and econometrics
GARCH-in-mean 模型
- 量化風險與報酬的權衡。
- 風險:$\sigma^2_t$。報酬:$\mu_t$。
- GARCH-in-mean 模型:
$$ \mu_{t} = \mu + \lambda \sigma^2_{t} $$
$\lambda > 0$ 為風險/報酬參數,表示每單位變異數風險帶來的期望報酬增量。
怎麼做?
把 ugarchspec() 的 mean.model 參數,從 list(armaOrder = c(0, 0)) 改為 list(armaOrder = c(0, 0), archm = TRUE, archpow = 2):
garchspec <- ugarchspec(
              mean.model = list(armaOrder = c(0, 0)),
              variance.model = list(model = "gjrGARCH"),
              distribution.model = "sstd")
garchspec <- ugarchspec(
               mean.model = list(armaOrder = c(0, 0), archm = TRUE, archpow = 2),
               variance.model = list(model = "gjrGARCH"),
               distribution.model = "sstd")
應用於 S&P 500 每日報酬
估計
garchfit <- ugarchfit(data = sp500ret, spec = garchspec)
檢視平均式的估計係數
round(coef(garchfit)[1:2], 4)
    mu  archm
0.0002 1.9950
預測的平均報酬
$$ \hat{\mu}_{t} = 0.0002 + 1.9950 \hat{\sigma}^2_{t} $$
預測報酬的時間序列圖
- 在 R 中繪圖
plot(fitted(garchfit))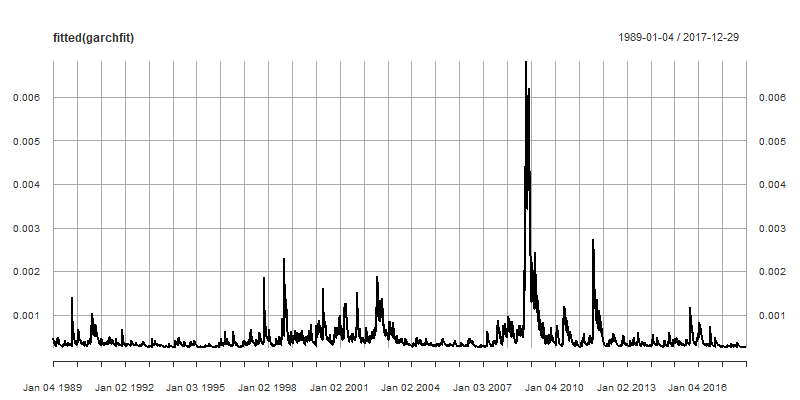
今日報酬可預測明日報酬
- GARCH-in-mean 以風險—報酬權衡的金融理論建立條件平均模型。
- 現在改用統計理論,建立能利用今日報酬與明日報酬相關性的平均模型。
- 最常見的是 AR(1) 模型:
- AR(1) 指的是 1 階自我迴歸模型。
- 以報酬相對長期平均 $\mu$ 的偏離來預測下一期報酬:
$$ \mu_{t} = \mu + \rho(R_{t-1} - \mu) $$
正的自我迴歸係數
$$ \mu_{t} = \mu + \rho(R_{t-1} - \mu) $$
- $\rho > 0$:
- 高於(或低於)平均的報酬之後,常接著出現高於(或低於)平均的報酬。
- 可能原因:市場對消息反應不足,因此報酬有動能。
- $|\rho|<1$:平均迴歸。$R_t$ 相對 $\mu$ 的偏離是暫時的。
負的自我迴歸係數
$$ \mu_{t} = \mu + \rho(R_{t-1} - \mu) $$
- $\rho < 0$:
- 高於(或低於)平均的報酬之後,常接著出現低於(或高於)平均的報酬。
- 可能原因:市場對消息反應過度,因此報酬出現反轉。
應用於 S&P 500 每日報酬
以 sst 分配的 AR(1)-GJR GARCH 之設定與估計
garchspec <- ugarchspec(
          mean.model = list(armaOrder = c(1, 0)),
          variance.model = list(model = "gjrGARCH"),
          distribution.model = "sstd")
garchfit <- ugarchfit(data = sp500ret, spec = garchspec)
AR(1) 模型估計值
round(coef(garchfit)[1:2], 4)
     mu     ar1
 0.0003 -0.0292
MA(1) 與 ARMA(1,1) 模型
1 階移動平均(MA(1))模型使用報酬相對其條件平均的偏離:
$$ \mu_{t} = \mu + \theta(R_{t-1} - \mu_{t-1}) $$
ARMA(1,1) 結合 AR(1) 與 MA(1):
$$ \mu_{t} = \mu + \rho(R_{t-1} - \mu) + \theta(R_{t-1} - \mu_{t-1}) $$
怎麼做?
MA(1)
garchspec <- ugarchspec(
          mean.model = list(armaOrder = c(0, 1)),
          variance.model = list(model = "gjrGARCH"),
          distribution.model = "sstd")
ARMA(1, 1)
garchspec <- ugarchspec(
          mean.model = list(armaOrder = c(1, 1)),
          variance.model = list(model = "gjrGARCH"),
          distribution.model = "sstd")
Your turn to change the mean.model argument
R 的 GARCH 模型

